Oil price advances as Iran backs production freeze
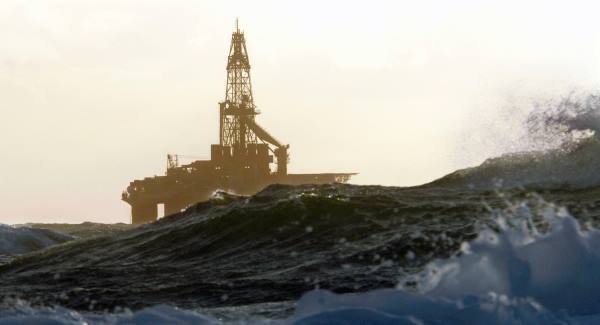
Futures in New York gained as much as 7.1%, reversing an earlier loss. Iran’s oil minister Bijan Namdar Zanganeh met with counterparts from Iraq, the second-biggest Opec producer, Qatar, and Venezuela following the output agreement in Doha on Tuesday. Iran supports the Doha proposal, Mr Zanganeh said, according to the Shana news agency.
He didn’t mention if the nation would deviate from plans to restore exports after the lifting of sanctions last month.
“The fact that they had a meeting and it ended cordially is reason enough for a gain,” said John Kilduff, a partner at Again Capital, a New York-based hedge fund that focuses on energy. “These countries are supposed to be at each other’s throats, so it’s something.”
Oil has dropped about 23% since the Organisation of Petroleum Exporting Countries effectively abandoned output targets in December.
Iran, the second-biggest Opec producer before sanctions were intensified in 2012, is seeking to boost output by one million barrels a day and regain market share after restrictions were lifted. The nation has loaded its first cargo to Europe, while Chinese and Spanish companies have also booked shipments.
US West Texas Intermediate oil for March delivery rose $1.85, or 6.4%, to $30.89 a barrel. Europe’s benchmark — Brent for April settlement — rose $2.39, or 7.4%, to $34.57 a barrel.
“Volatility is through the roof,” said Stephen Schork, president of the Schork Group in Pennsylvania. “We’re in the midst of a technical rebound. The market is oversold and using these headlines hinting at Opec getting its act together as an excuse.”
Iran will “not forgo its share of the market,” Mr Zanganeh had said on Tuesday, according to Shana. The nation pumped 2.86m barrels a day in January, making it the fifth-biggest producer in Opec.
Iraq is ready to join Saudi Arabia in freezing or cutting output if others commit to the accord, said an official who asked not to be identified.
“The Iranians sacrificed a great deal to get the sanctions lifted and are very much focused on bringing production online,” said Chris Lafakis, a West Chester, Pennsylvania-based senior economist at Moody’s Analytics. “They have said that they aim to increase output by one million barrels a day, but that’s easier said than done.”
Even if producers reach agreement, the deal would have little impact on production and would “leave the global surplus in place” in the first half of 2016, Goldman Sachs analysts Damien Courvalin and Jeff Currie said in a report. Iran’s determination to expand output suggests its participation is unlikely, they said.
The preliminary deal to fix production at January levels is the “beginning of a process” that may require “other steps to stabilise and improve the market,” said Saudi oil minister Ali Al-Naimi.

CONNECT WITH US TODAY



Be the first to know the latest news and updates