David McNamara: Bond markets show strains of global uncertainty
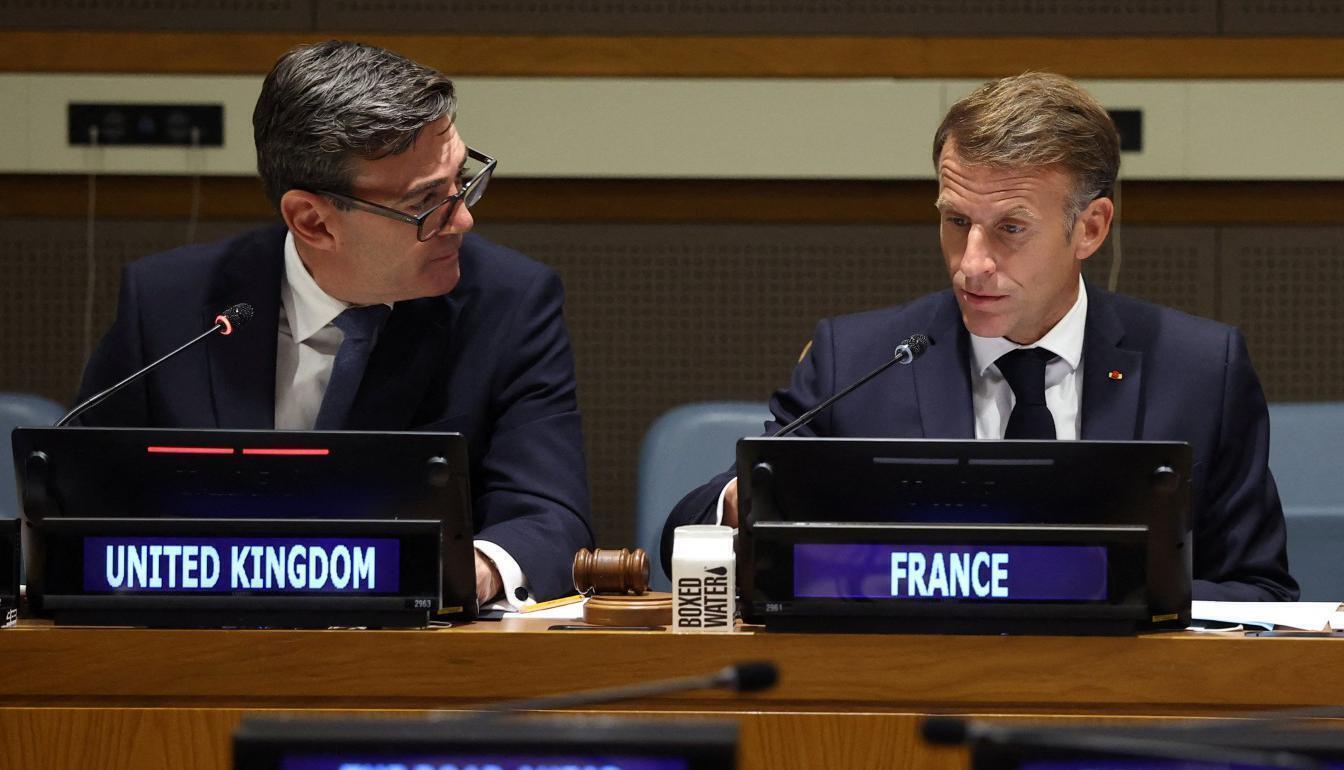
UK Prime Minister Andy Burnham with French President Emmanuel Macron. France, Italy, and the UK have endured significant rises in 10-30 year borrowing costs to 20–year highs in recent days. Picture: Toby Melville/PA Wire

Amid continued volatility in sovereign bond yields, a remarkably stable feature of markets has been in bond spreads, with little signs currently of a surge in corporate spreads, as was seen following the last inflation shock in 2022.
Due to the ongoing uncertainty on the outlook for inflation, markets are pricing in a succession of rate hikes over the next year, of up to an additional 100 basis points (bps) of tightening across the major central banks. This would take official rates back to, and beyond in some cases, the peaks reached following the inflationary surge in 2021/22.
Given the relatively muted trends in headline inflation versus that previous shock, current market pricing looks over done. Nevertheless, it is driving both the front-end and long-end of interest rate curves. However, underlying this inflationary catalyst, markets are also pricing in greater term premia on governments with patchy records of delivering on deficit and debt reduction, and on general political uncertainty. In this regard, France, Italy, and the UK have endured significant rises in 10-30 year borrowing costs to 20–year highs in recent days, while also seeing spreads widen to safe havens such as German bunds.
In contrast, corporate spreads remain close to historic lows, both in Europe and the US, trading between 50-80bps above risk-free rates. This is in stark contrast to the dramatic blow-out in corporate spreads in 2020 during the pandemic, and in 2022 following the invasion of Ukraine. The difference today likely reflects several factors including the relatively contained nature, for now, of the conflict in the Middle East, the broad robustness of corporate balance sheets, and the sheer weight of capital now being deployed towards the AI build-out in credit markets.
However, the AI investment cycle in the US and globally is set to rival if not surpass previous super cycles in real estate and telecoms in the 1990/2000s, and even the railroad boom of the 1800s. This raises the very real risk of a sudden market correction spreading from equity to credit markets in short order, if the expected returns on investment do not materialise as quickly as consensus estimates are pencilling in.
Some have also pointed to the AI investment boom as exacerbating the rise in sovereign bond yields amid what Fed chair Kevin Warsh called the “competition for capital”. Other sectors of the economy are also experiencing a dearth of investment, most notably the commercial and residential real estate sectors in the US, which have seen a collapse in construction activity over the past 18 months.
Irish government borrowing costs have also risen this year, albeit not to the same extent as elsewhere. However, the global trends of higher rates and inflation are a salutary lesson for a Government embarking on a €275bn National Development Plan over the next decade. Achieving value-for-money in the current environment will be the primary challenge for policymakers. Failure to do so will not just cost money now but it may also cost more in interest payments further down the line.