LIV Golf secures up to €268m funding commitment for 2027 relaunch
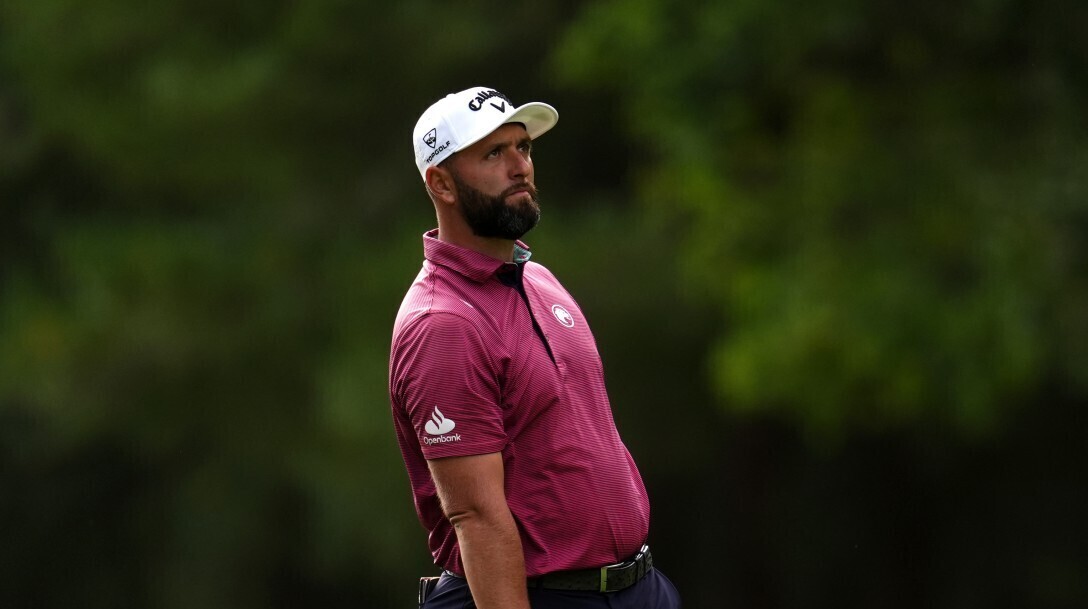
Reports suggested Jon Rahm is owed up to €134m ($150m) for the remainder of his LIV Golf contract. Pic: Adam Davy/PA Wire.
LIV Golf has secured an initial funding commitment for a potential €268m ($300m) investment from BC Partners Credit to help relaunch in 2027.
The breakaway series filed for bankruptcy last month after Saudi Arabia’s Public Investment Fund – which had spent €4.5bn ($5bn) in four years – announced it was withdrawing support at the end of the season.
That cast the future of LIV into doubt but a deal with BC, subject to approval from the bankruptcy court, gives it the chance to reset next year.
BC signed a term sheet with LIV last month, requiring it to sign half of the players to whom it owes money, as part of its financing plan.
Read More
However, there is no obligation for the current crop to rejoin, with Sergio Garcia last week submitting court papers asking for his contract to be terminated.
The bankruptcy papers showed LIV owed €57 ($64m) to its top 27 creditors, with €40m ($45m) owed to current and former players at the time of the filing, but did not include future obligations.
Reports suggested Jon Rahm is owed up to €134m ($150m) for the remainder of his contract.
“Our goal is to facilitate LIV Golf’s emergence from the restructuring process on sound financial footing and with renewed momentum heading into the 2027 season,” said Ted Goldthorpe, partner and head of BC Partners Credit.
The first of several hearings related to the bankruptcy will be held later this week.
“We’re delivering on our major milestones, and while there is still work ahead, today marks meaningful progress toward a player-owned, team-focused, truly global league that complements the wider game and creates new opportunities for players, fans, partners, and the next generation of golfers,” LIV Golf chief executive Scott O’Neil said.
CONNECT WITH US TODAY


Be the first to know the latest news and updates