Retracing milestones in evolution of pensions
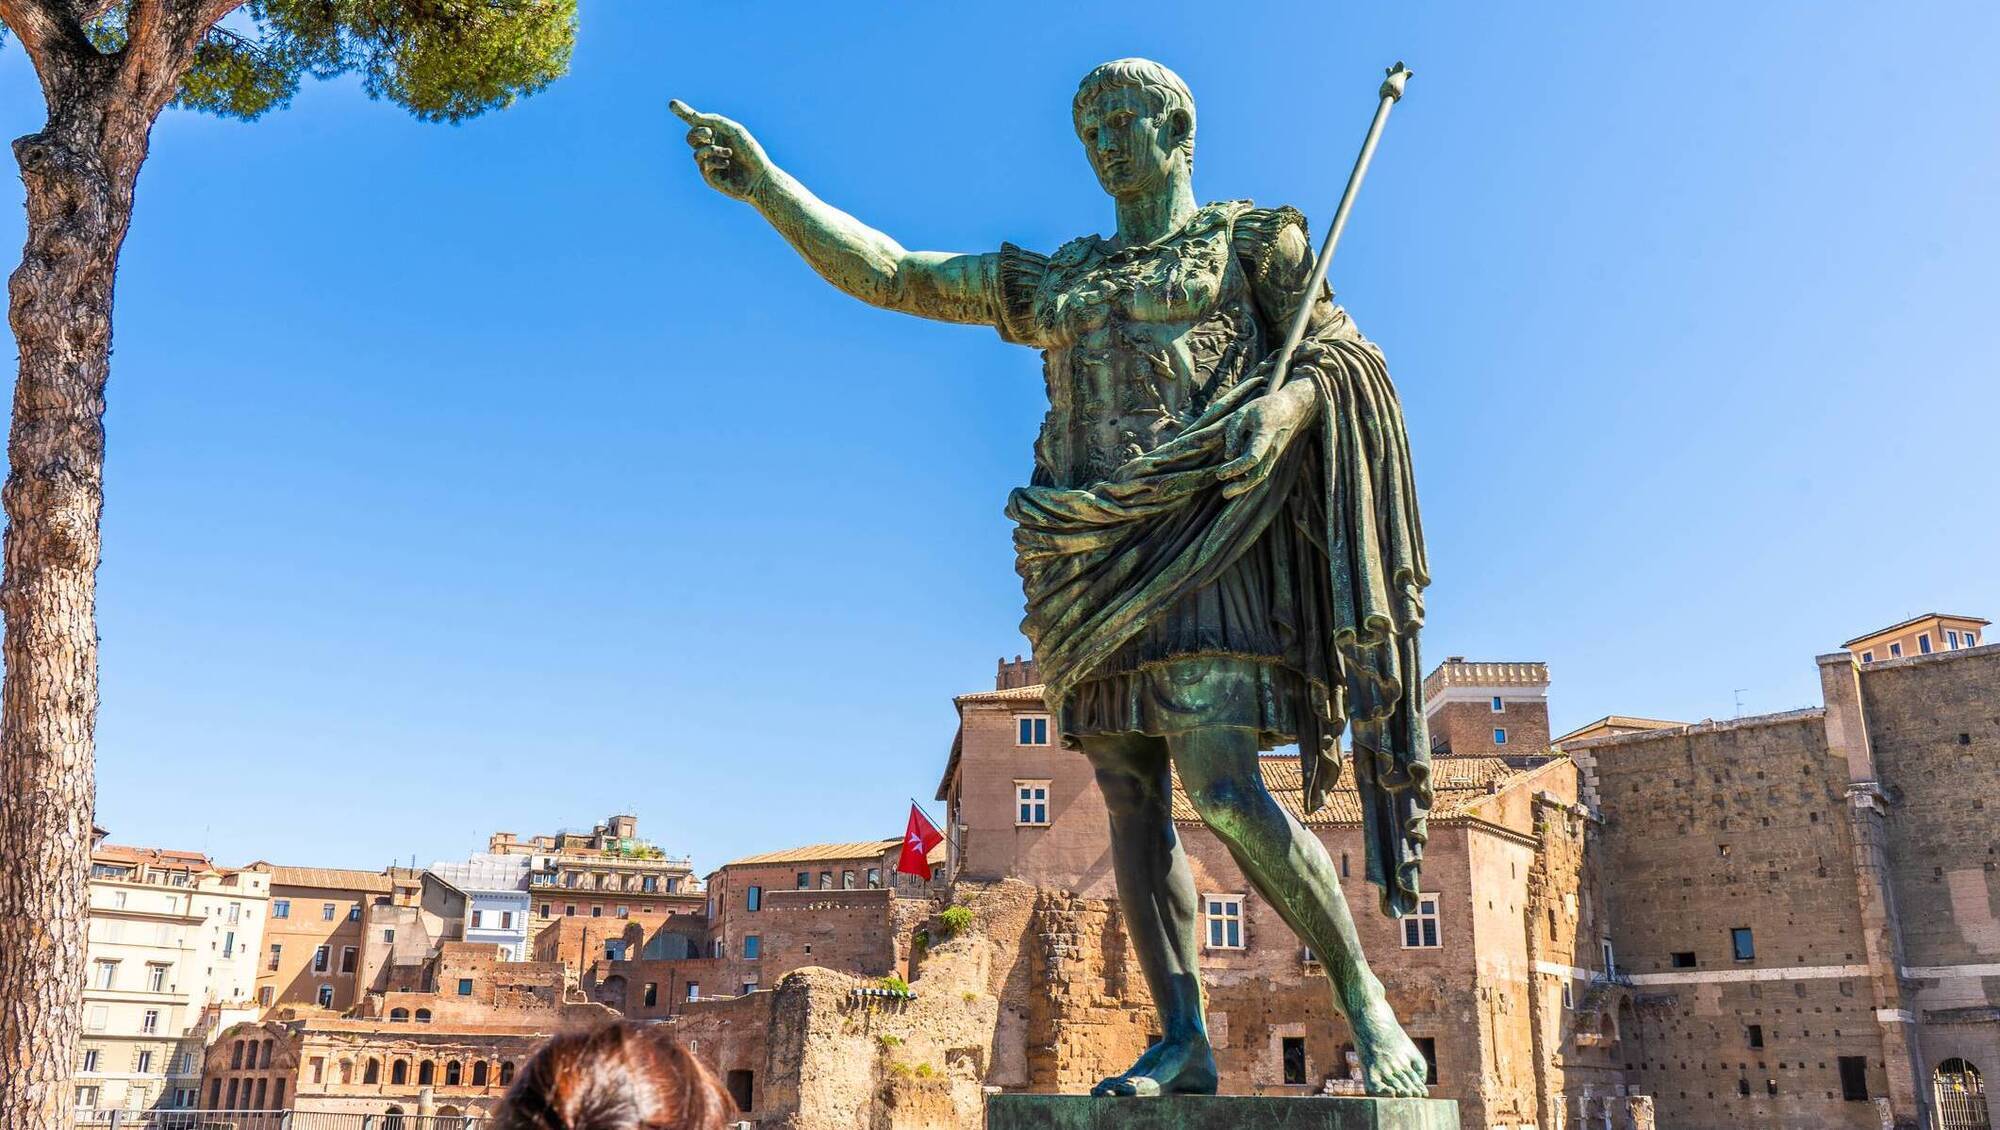
Emperor Caesar Augustus, who led the Roman Empire for over forty years (27 BC to 14 AD), who is credited with inventing the world’s first ‘contributory’ old age pension.
Although it can seem that the pension and financial planning industries are a modern construction, they have been around in some form for thousands of years. Among many milestones in their development, here are some historic highlights.
Some historians of ancient Rome argue that Emperor Caesar Augustus was the most effective politician ever to live. Despite his constant assertion that he was just an ordinary citizen with a few more responsibilities than most, he somehow managed to rule the most successful Empire the world had yet seen for over forty years, and modestly declared that “I found Rome a city of bricks and left it a city of marble.”
His political superpower was his ability to see around corners, to anticipate a problem and solve it before it became a knife in the back on his way to the Forum. This gift of foresight prompted Augustus to invent the world’s first ‘contributory’ old age pension.
For centuries Roman armies had been manned by soldiers who signed up for a specific campaign and, after a couple years of lucrative plunder, headed home again to live on the spoils of war. But when he effectively ended the Republic, Augustus needed a standing army loyal to him personally and not burn the city if they completed twenty years of military service with empty pockets. He didn’t feel that having thousands of disgruntled killers with access to modern weaponry around the place would be conducive to his long-term health and wellbeing.
So, he created the aerarium militare, a permanent pension pot for retired soldiers, funded by a combination of a hefty personal donation, an ongoing 5% inheritance tax and a 1% levy on auction sales. It was a typically wise move which helped ensure that he died peacefully in his own bed, a luxury denied to most of his successors for the next five centuries.
When the Roman Empire eventually fell, the aerarium militare went with it and care for the elderly reverted to existing cultural and tribal norms. The Irish performed particularly well. Under the ancient Brehon system there was a legal compulsion on family or kin to provide a care for their aged or dependent relatives including a guaranteed amount of food, a place to live, clothes, medicinal remedies when needed and a decent burial when the sad time came. In order to pay for all this the dependant pensioner, would transfer land to pay forward on the arrangement. In modern pension parlance, the transferred assets were the PRSA fund which the caring family converted to a lifelong ARF.
Even though the Brehon Laws were formed in a pagan, druidic society, the Christian monks of the medieval monasteries were not too full of sanctifying grace to plagiarise their work. Religious houses devised a similar system known as ‘corrodies’ which for an upfront payment or land transfer, the monastery would legally contract to provide lifelong bed and board. Selling financial products wasn’t a stretch for monks back then. For a few pennies they would free a beloved relatives soul early from purgatory and a few gold pieces would secure you a fragment of the true cross. But they lacked the actuarial precision of modern times and tended to underprice the pension contribution. Many funds ran out of assets, and their solution was just to sell more corrodies for higher prices and use the proceeds to pay current liabilities to pensioners who inconveniently lived too long. Gods ponzi pension scheme.
The monk-made ‘pension deficit crisis’ became particularly problematic to King Henry VIII. When not dispatching unfortunate wives, he spent the 1530’s suppressing the monasteries and ‘nationalising’ their assets in order to feed his glutinous treasury. He wasn’t too pleased to discover that as well as all the land, gold, and art he annexed, he had also acquired lots of expensive legally binding contracts to feed, cloth, house and bury thousands of his subjects. It would have been politically dangerous even for him to walk away from such an important social contract, so he converted the liabilities into fixed cash pensions which were paid out from the treasury, an early example of a nation state paying an annuity to citizens.
In the centuries following the death of King Henry, differently flavoured schemes began to pop up all over Europe and participation was generally based on community, city, or craft. One of the more enduring, or infamous of these, was the system devised by an Italian banker named Lorenzo Di Tonti in the 1650s. His ‘Tontine’ system was a loose combination of a mortality lottery, a life insurance scheme, and a present-day defined benefit scheme. To join the plan, a capital sum was invested, and this entitled the investor to an annual dividend for life. Upon death this dividend was reallocated to the living members and so on until the last man standing was paid all the annuities from the scheme for life. When there was no one left to pay, the invested capital was reallocated to the state treasury or the scheme’s promoters.
Tontines gained popularity both in Europe and in the new worlds, but there were a couple of glaring weaknesses in the product that eventually caused their demise. Firstly, it was to a member’s advantage if fellow investors died sooner rather than later and rumours abounded that many were helped on their way, tragically early. Secondly, cleverer investors realised that a child, specifically a girl, who survived to the age of five was statistically likely to live a long life. So, Tontines were purchased for young nieces, daughters, and grand daughters who tended to survive for longer than the funds available to pay their annual dividend.
By the time Otto Von Bismarck proclaimed the German Empire in 1871 tontines had fallen out of fashion. But his united confederation gradually came under increasing electoral and political pressure from left wing parties, and he needed a carrot to lure his populace away from the dangers of socialism. This was the thinking behind his landmark 1889 law which established the first modern state pension plan. Just like the MyFutureFund launched in Ireland earlier this year, the scheme was funded by a combination of employer, employee and state contributions and was payable at the age of seventy, which was reduced to sixty-five in 1916. The ‘Bismarck Model’ became the basis for almost every state sponsored old-age pension scheme ever since.
The first equivalent Bismarck scheme in Ireland was introduced in 1909 with the passing of the Old Age Pensions Act at Westminster. Citizens who passed a means test were entitled to receive five shillings a week when they reached the age of seventy. But proving your age wasn’t as simple as it sounds because the registration of births only started in Ireland in 1864. By 1923 the weekly stipend had doubled, but with independence came severe fiscal pressure as well as the freedom to make daft political mistakes.
Somehow, the Free State’s first minister of finance, Ernest Blythe, thought it a clever idea to dock old age pensions by a shilling, a political calculation that unleashed the ‘grey power,’ eventually cost him his seat and shredded his reputation for generations. Caesar Augustus would have been a much too cute political ‘hoor’ to make this mistake, but unlike the greatest Roman politician, poor old Ernie couldn’t see around corners.