Home Q&A: My parents want to advance some of my inheritance as a house deposit
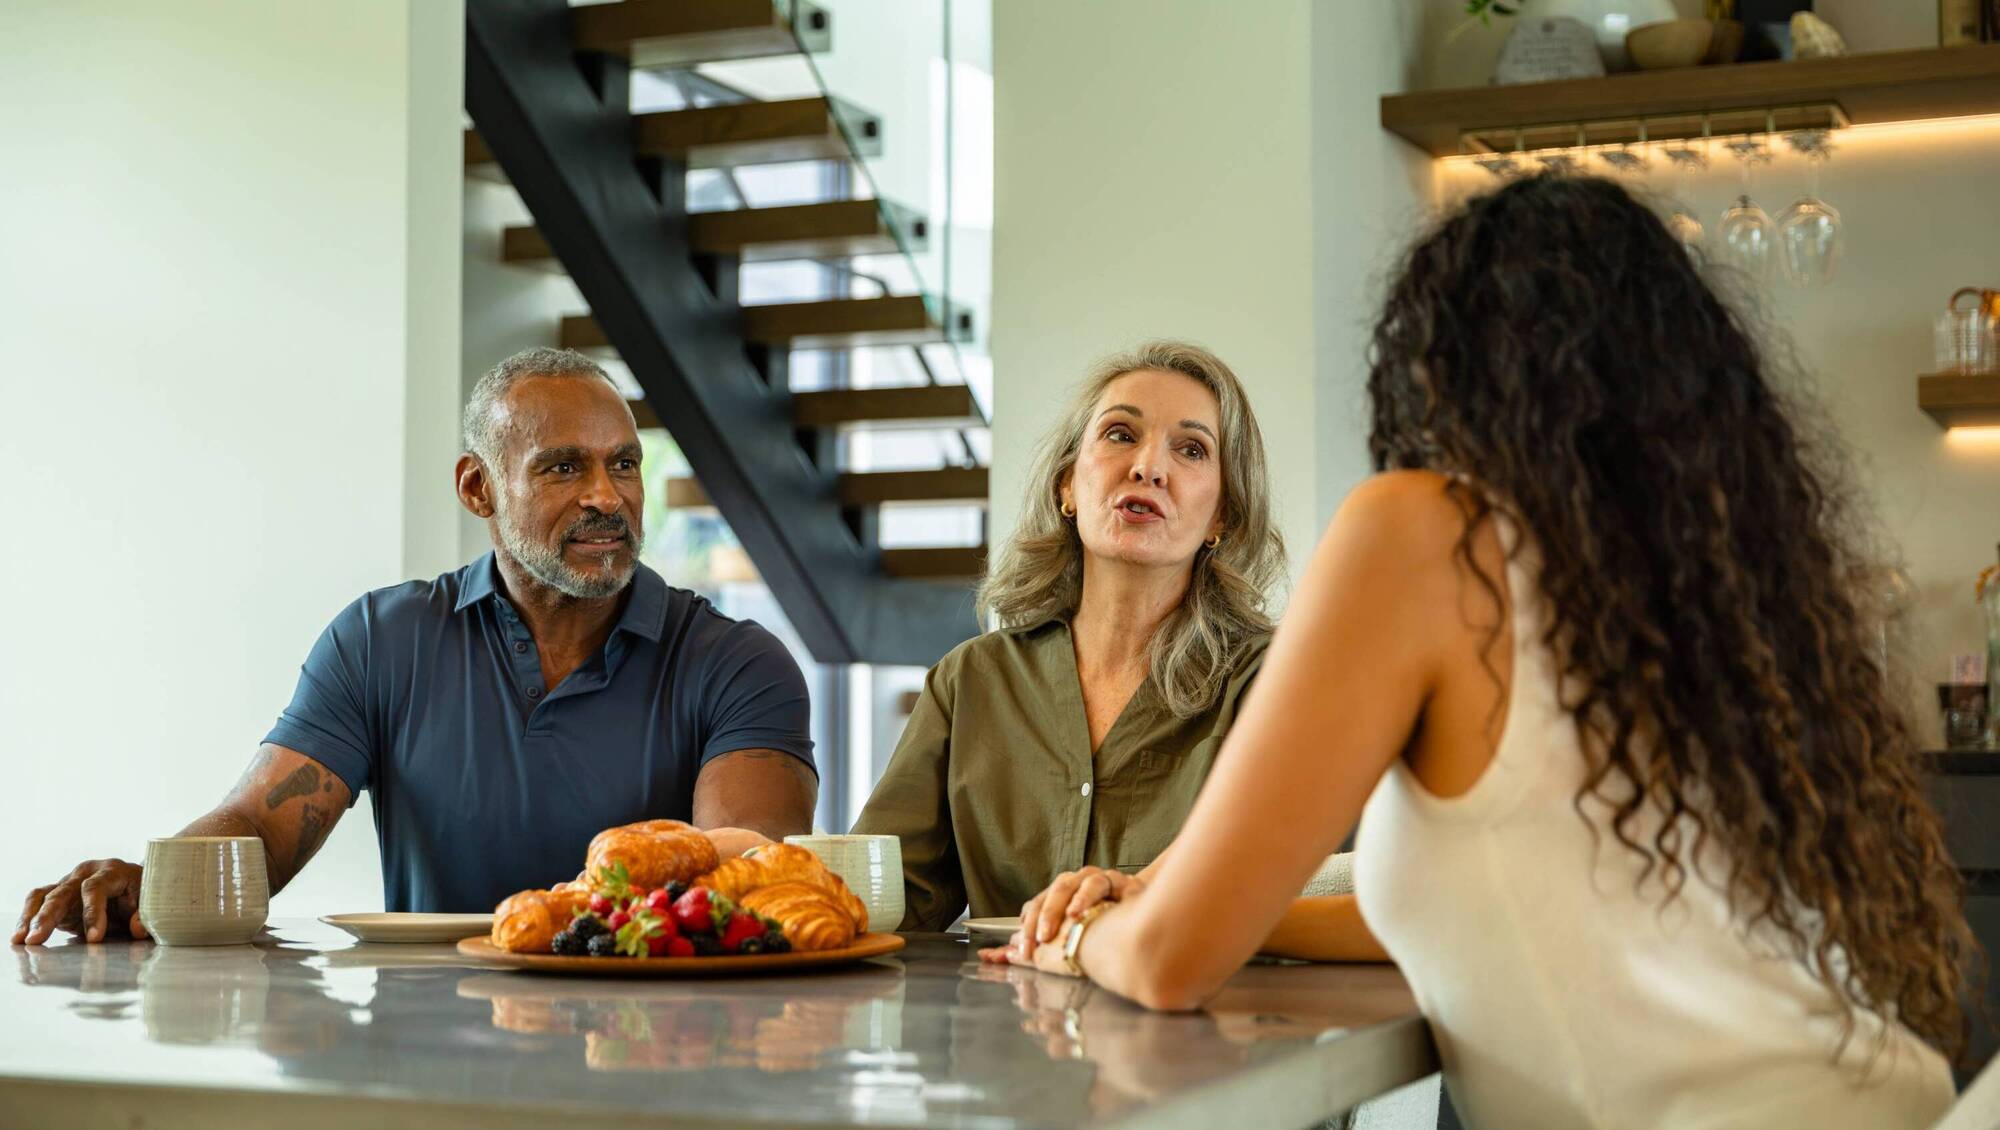
A full, frank discussion is vital when exploring the gift of a property deposit or any financial help from a parent or family member. While it may come to fruition, a clear “no” should be respected. Always get independent financial advice. File picture
The use of intergenerational wealth continues to evolve as an increasingly important tool for younger buyers whose parents or relatives have the means to row in on a deposit for a mortgage agreement. The old income-to-wage multipliers that were used by lenders to provide mortgages based on a reasonable wage and a deposit as a percentage of the sale price of the home are proving an impossible vector for many working individuals and couples. With the affordability gap yawning wide, mortgage repayments and deposits simply don’t add up for many young professionals and trades who would in past years have easily qualified for a house buy. Prices have outstripped wage growth, leading grown adults back to the Bank of Mam and Dad. This macroeconomic moment, beyond the control of a son or daughter, is an excruciating ask, but an increasingly familiar prospect.
According to the latest data from the Banking and Payments Federation Ireland (BPFI), first-time buyers (FTBs) continue to drive the mortgage market, accounting for 60% of the volume and 61% of the value of mortgage drawdowns in 2025 (bpfi.ie). Martina Hennessy, CEO and founder of mortgage broker Doddl.ie, says, “This year, 31% of our clients received a gift, with first-time buyers making up 90% of all gifted funds. Gift amounts year to date have ranged from €1,500 to €425,000. 16% of the gifts received by our clients were over €100,000, and €10,000 to €25,000 is the most common gift range.”
Boomers and Generation X are currently being maligned on social media as smug, fat-cats with pensions, savings and mortgages already paid off. We’re not going to get into the nastily parsed arguments surrounding whether these assets should be liquidated and partly redistributed to younger members of the family. Parents have their own financial and emotional pressures to navigate. They may be working, retired or quite elderly. With life expectancies rising, grandparents may both be still with us. Property, inheritances and savings can be tied up as elder care takes priority. Welcome to the new challenges of the Sandwich Generation.
Even with the Help to Buy (HTB) and First Home Scheme, many grown adults with good jobs will have to ask a deeply uncomfortable question of their parents, who may feel their financial position is under scrutiny.
What devices could be used to provide funds for someone else to use as a deposit on a home, or as additional funding to buy? Personal savings and investments can be released, of course, and then there’s the prospect of an equity release on the house that the parents are living in (see our explainer).
The Small Gift Exemption is a very useful device if planned for over a course of years. This is an annual gift of €3000 from each parent allowed as a tax-free gift outside of lifetime gifts and inheritances. Given by each parent, that adds up to €6000 a year. This gift can be given to anyone, not just children.
When planning ahead and saving in their name, using the Small Gift Exemption from the time children are young is a popular way to save for their future without hidden tax implications. Even if you have adult children a few years out from a home purchase, and have not used the Small Gift Exemption before, consider starting. Each parent can also give the legal partner of their child up to €3000 per calendar year too, another €6000 annually if both parents are still living and contribute. A properly recorded deposit trail, year-on-year, is expected by Revenue if a lump sum for a deposit is built up from annual, tax-exempt gifts.
If a parent gives a lump sum to the child, that’s over and above the parameters of the Small Gift Exemption; it will be counted as part of their lifetime gifts and inheritance. Gifts are calculated for tax just as an inheritance would be, with the same thresholds before taxation becomes due depending on the person’s relationship to the giver. The threshold for children and step-children is a lifetime amount of €400,000 at present. Gifts and inheritances are self-declared to Revenue, but keep all those records in case of an audit.
If, as a parent, you hand a bulk sum that meets 80% or more of the child’s Lifetime Gift Threshold (maximum this would be €320,000), this will trigger an IT38 CAT Return to Revenue. Both parties must get independent financial advice if getting involved together in a property deal. This would include any gift, and where parents are acting as mortgage guarantors or participating in joint mortgages.
Martina Hennessy says, "A bank will want to know the source of all funds going toward purchase, and when it comes to a gift, they want to ensure that the gift is non-refundable and that the giftor is aware that they have no rights or interests in the property by virtue of the gift. A gift letter or deed of confirmation will be required for mortgage purposes to confirm these items. If the gift is over the CAT gift tax threshold, the applicant will need to show how they will meet the tax liability. Even if a gift covers the full 10% deposit or more, a bank will generally want to see some savings by the applicant and will want to see a clear ability to repay the mortgage.”
What about Help to Buy (HTB)? Can those in receipt of a gift still avail of this scheme? Martina says, “First-time buyers who are purchasing a new build home or building a home up to a value of €500,000 may be eligible for HTB. This is a rebate of tax paid in the last 4 years and can be 10% of the purchase price, capped at €30,000. One of the rules that apply to help to buy eligibility is that the loan to value cannot be less than 70%. As such, if a large deposit or gift applies such that it is more than 30% of the purchase price or value, then you will be ineligible for the help to buy.”
If, as property seekers, we are gifted a deposit or a large gift, can we assume we can borrow more? “This is not the case,” says Martina Hennessy. “Your ability to borrow is based on your income and your ability to repay, so regardless of the funds you will be contributing towards the purchase, central bank loan-to-income rules will still apply for assessment. Lenders tier their rates by loan-to-value; most first-time buyers struggling to get a 10% deposit in place will have a 90% loan-to-value. If there is a significant gift and the total deposit funds are 20% or higher, the interest rates that can be available will be lower. There can be a 0.5% difference in the interest rate once you hit the 80% loan-to-value bracket, and this can have a meaningful impact on repayments."
What if we are gifted or gifting as site? How does the bank handle this in terms of the mortgage? Matina Hennessy says, “If an applicant is planning a self-build and is being gifted a site, then the site can be used as part of their deposit and provided the overall loan-to-value on completion of the house is 90% or lower, then you can finance up to 100% of the build cost."
Finally, the way this question was worded to me, it’s not clear if the parents involved have decided on the gift of a deposit. If anyone in your life voices that they cannot, or do not want to give all or any of the money requested for a deposit, my advice would be to use your emotional intelligence and respect their word, even if their reasons are not made completely clear. Familial history can be deep and difficult.
After the stress and sacrifice of, for instance, guiding someone through three to five years of college, resources may be falling and resentment rising. Financial fatigue is real. Perhaps the subject can be tabled again, in the presence of a wealth specialist who will take a holistic look at the whole financial picture (this would not be the estate agent selling a property). Pleading, barging through personal boundaries, or worst still, bullying someone into a gift or loan? Even if (prompted by valid financial stressors) you get your way, the effect on these precious connections in your life could be disastrous.
- Got a question for our Home team? Email. home@examiner.ie
CONNECT WITH US TODAY


Be the first to know the latest news and updates