Central Bank borrowing limits - Preventing excess must be welcomed
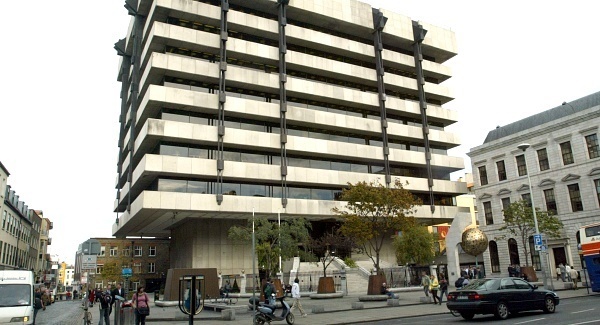
Central Bank economists say banks should not lend more than 80% of the value of a property, and that borrowers should not get a mortgage of more than four times their income. This would make both banks and households more resilient in market downturns, according to research conducted on behalf of the bank.
Why the research? A child of 10 could have told them that.
Restricting borrowing to what people can reasonably afford is both sane and sensible, in contrast to the madness of the mid-noughties when banks were handing out more than 100% mortgages to almost anyone who applied. It was commonplace for borrowers to be encouraged to add furniture, cars and even boats to their mortgages, such was the level of insanity that prevailed.
The pity of it is that our financial regulators did not insist on such prudence years ago. Even now, the recommendation comes only in the form of a research note and is nowhere near becoming official policy.
The Central Bank is likely to publish a consultation paper next week calling for submissions on the feasibility of introducing binding measures to restrict loans. The proposal is twofold: a cap on loan-to-value ratios that would impose a minimum down-payment level on prospective purchasers. There would also be limits on loan-to-income ratios to constrain the ability of households to borrow at unsustainable levels.
Both forms of limits are in operation in Norway, Sweden Finland, New Zealand, Hong Kong and have just been introduced in a limited way in the UK. In Britain, the Bank of England – which is, essentially the central bank of the UK –has introduced curbs on lending from the start of this month. Lenders are to be prevented from allocating more than 15% of new residential mortgages to individuals borrowing four and a half times their income or greater.
If the measures proposed here are implemented they will represent the first limits on the mortgage market in decades by tightening the affordability tests that prospective homeowners face when applying for a mortgage. Prudence is the key to proper lending practices but the banks cannot be relied upon to act responsibly in all instances, so a measure of enforceability will be necessary. Already some lenders are offering ‘teasers’ to would-be homeowners by offering, for instance, to pay stamp duty on houses.
A report published by stockbroker Davy this week questions current lending practices and says there is an onus on the Central Bank to put limits in place.
The Central Bank move also comes as property prices begin to soar again, with prices in Dublin up 25% in the past year and other big increases elsewhere. Any measure that can curb the excesses of recent years is to be welcomed but they must come with proper enforcement measures against lenders.
CONNECT WITH US TODAY


Be the first to know the latest news and updates