Revolut made banking easier. But what happens when millions lose access to their money?
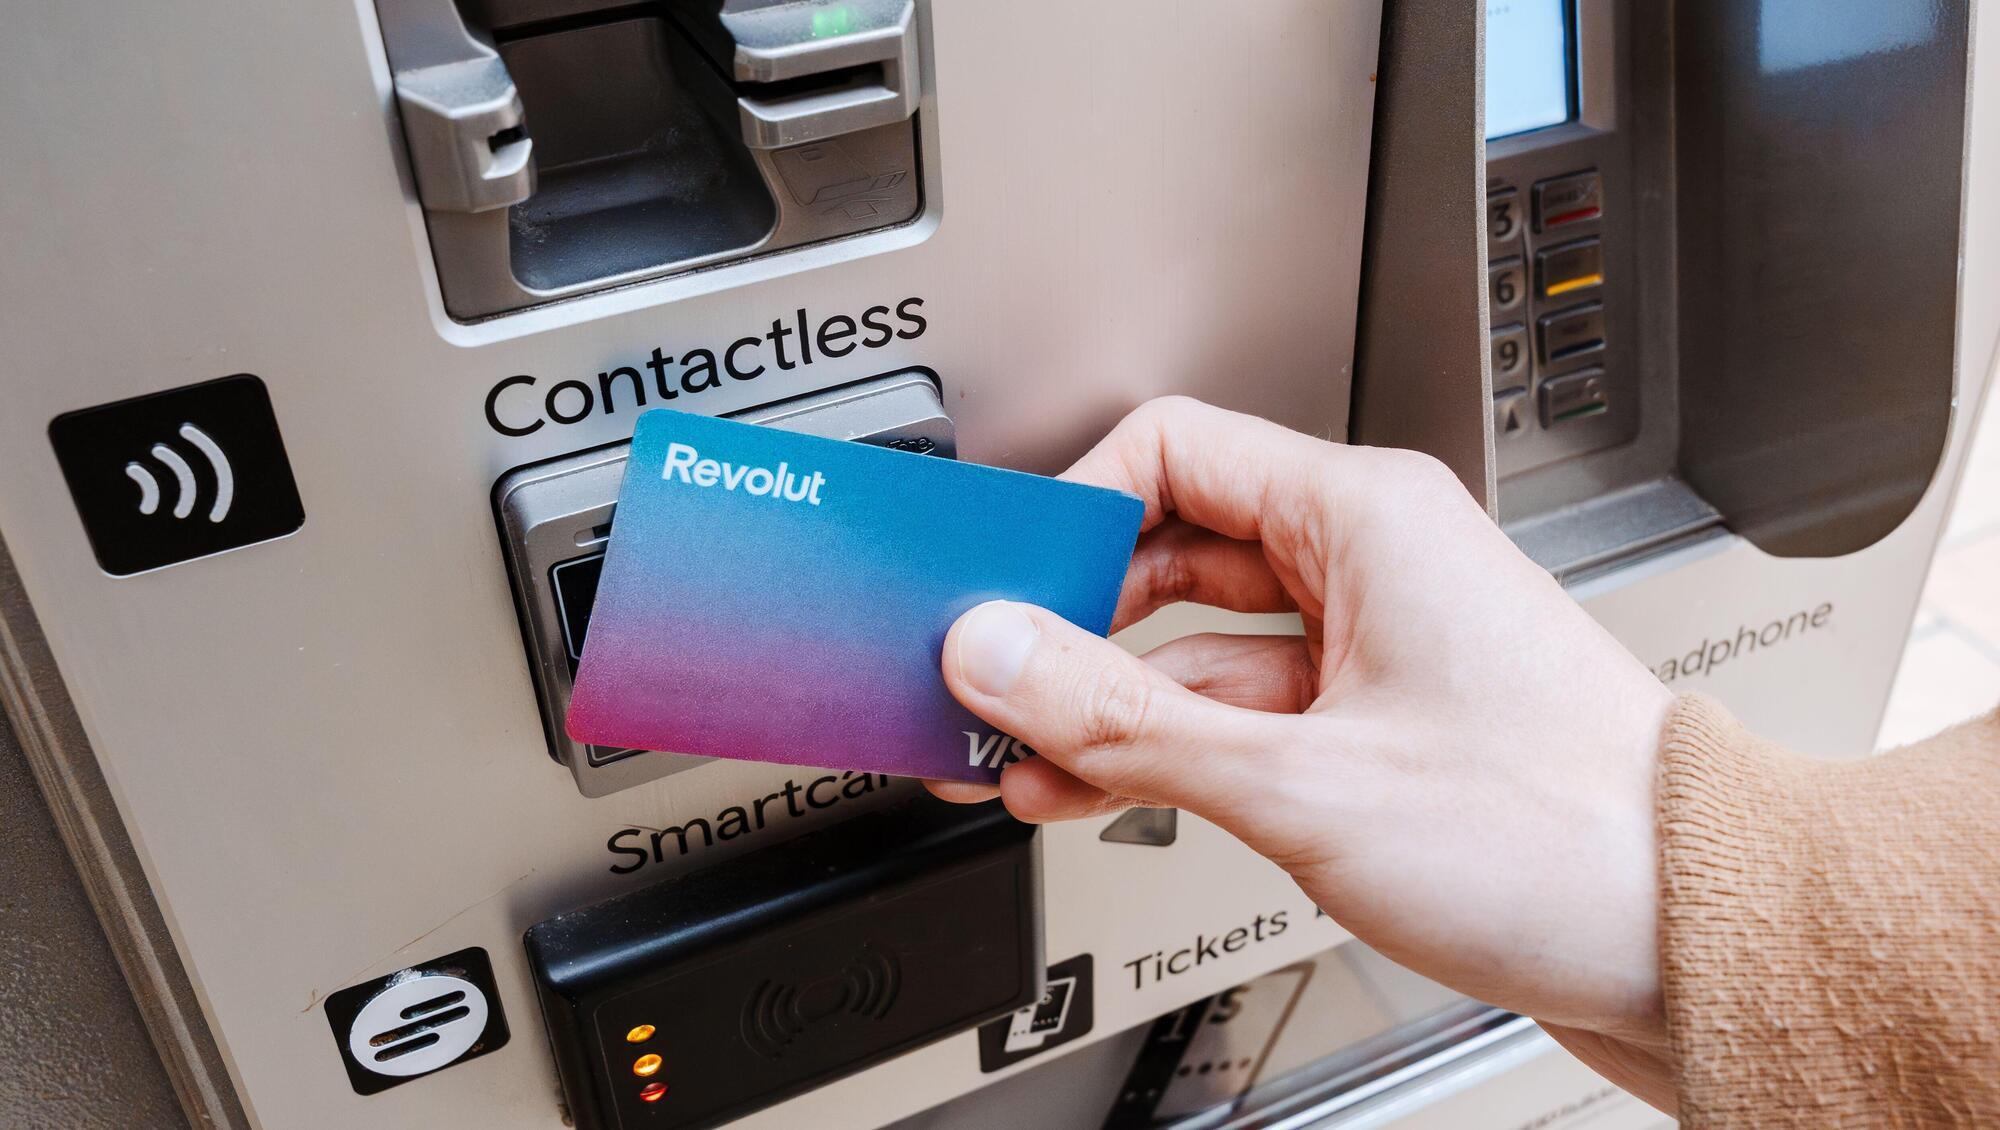
In August, total spending on cards by Irish consumers stood at €9.72bn.
Digital banking, but Revolut in particular, has become ubiquitous throughout daily life, with an ease of use that has shown up the traditional banks in Ireland, leaving them all to play catch-up.
However, an outage earlier this week also showed some of the pitfalls that come alongside that ease.
The latest data from the Central Bank of Ireland shows during August, total spending on cards by Irish consumers stood at €9.72bn — an increase of 2.39% compared to the same month in 2025. The number of transactions was up 8.29% year-on-year to 264.74m. The size of the average transaction fell to €35.77, down 6.46%.
The value of contactless payments stood at just over €3bn, which includes €2.19bn for payments via digital wallets.
While card spending increased, the volume and value of cash withdrawals have declined. In August, €1.04bn was withdrawn across 6.82 million transactions. Year-on-year, both the value and volume fell by 4.29% and 7.17% respectively.
The 2025 Access to Cash legislation was put in place to ensure there would always be a ready supply of cash for consumers, but just because cash will be available doesn’t mean consumers’ growing preferences for card and digital wallet payments are going to slow down any time soon.
Due to this growing dependence on card and digital payment systems, any disruption to these systems is going to cause widespread issues for customers, as seen with the Revolut issue.
On Tuesday this week, Revolut reported a service disruption which resulted in some of its services being inaccessible to customers. The outage was not limited to Ireland, as the bank’s services were down for many of the users. The digital bank has a huge customer base in Ireland, with 3.4 million users, with a total of 80 million worldwide.
Read More
The outage was not Revolut’s fault, and it wasn’t limited to the bank, as it was as a result of a problem with Google Cloud, on which the service runs its operations.
However, this points to the inherent vulnerability in these systems: Revolut is never fully in control of its own services and a disruption from one of its vendors can in fact hurt its customers.
Professor Olive McCarthy, of Cork University Business School, said a “sole reliance” on digital payments could “create difficulties” for consumers, particularly cyberattacks, wars or other outages such as the one seen with Revolut earlier this week.
“Such incidents are rarely predictable and certainly don’t wait for a time that’s convenient for consumers. Increasing choice for consumers in payments services is to be welcomed as it supports economic resilience and competition,” she said.
“Maintaining use and acceptance of cash are also essential.
When the Revolut outage was first noted, the digital bank was quick to reassure customers their money and data were safe and it was working to fix the issue. However, customers were left without access to their money and unable to use it throughout the course of the day.
Revolut apologised to customers for the inconvenience but added the issue was with Google Cloud and not it.
Services were restored to customers by the end of the day on Tuesday but there is still the matter of what happened to transactions that could not be processed at the time.
In a statement to users, Revolut said if a card transaction was made during the period of disruption, including a card refund, “it may take a few days for your balance to update and the transaction to appear in your account”.
“We’re working to process these transactions as quickly as possible… If you have any questions or outstanding issues, our support team is available 24/7 via our in-app chat.”
However, there is still the issue of a customer who, having had their Revolut card payment declined during the disruption and paid by other means, potentially being double-charged when the transaction is eventually processed.
The understands Revolut is actively monitoring reports from customers who may be experiencing duplicate transactions or declined transactions appearing as approved and it is working towards resolving these discrepancies.
While Ireland may not be Revolut’s biggest market, it has been referred to as one of its “strongest markets”.
When the company published its annual results for 2025 earlier this year, it noted an 18% increase in the volume of peer-to-peer transactions last year, as well as a 30% increase in the total value processed.
Customer balances grew by a further 56% in Ireland in 2025 compared to 2024, while savings balances grew by almost 73% year-on-year. It also noted almost 33,000 firms in Ireland used Revolut Business as of the end of last year — a 22% increase.
Even though Revolut was not at fault for this most recent outage of its services, it comes at a difficult time for the company. Last month, it suffered two different data breaches in which customers lost data.
On September 14, Revolut informed customers criminals had obtained personal information including passport and driving licence copies, dates of birth and contact details.
The company said an “unauthorised third party” had used an email domain from a legitimate government agency to submit “fraudulent requests for information”.
While Revolut did not disclose the number affected, reports suggested about 700 customers worldwide, including approximately 12 in Ireland, had been impacted.
In late September, Irish customers were also among those potentially affected by a breach at DriveWealth, a US broker that handles stock trades for Revolut customers.
DriveWealth said unauthorised access may have exposed customer names, contact details, addresses, employment information, biographical data and partial account numbers.
The outage and the data breaches come at a critical time when the company is also exploring an initial public offering that could see it list its stock in the US. It is seeking a valuation of about $115bn (€102.5bn). It has also received preliminary approval for a banking licence in the US after getting similar licences in France and England.
The success of Revolut in Ireland has forced the traditional banks to play catch-up, launching features the company has had for years. However, as customer finances become more digital, service outages and potential data leaks and breaches can become even more problematic for users.
Over the last few months, AIB has rolled out its newly updated banking app, which aims to give customers easier access to payments, enhanced security, access to savings accounts within the app, the option to invest money through its AIB Life hub, as well as the option to utilise Zippay for instant payments between the three pillar banks.
In its new app, AIB also launched a new AI chatbot to deal with customer issues and queries.
Bank of Ireland also revamped its app with some additional changes to payee management and layout design, as well as the additional feature of being able to quickly blur balances and freeze or unfreeze cards.
In addition, the digital bank Monzo launched in Ireland, explicitly selling itself on its customer service record. It quickly garnered 100,000 users but it is potentially susceptible to some of the same issues Revolut had to deal with.
Credit unions, which offer many of the same services as traditional banks, do have a digital component but it is not chasing changes in these areas to the same extent the pillar and digital banks are.
Chief executive of the Irish League of Credit Unions David Malone said different banks could have a “digital app with nothing behind it”, with no people to support customers.
“A digital Mary Celeste,” he said, "we're not a digital Mary Celeste. We do have a digital offering, but also we have the human interaction.”
“So we're giving people the choice. We are on a digital transformation journey. We'll use digital where it works for the member, but then it frees up our most important resource, which is [the credit union] staff, to help tailor more products and services for the members of the public.”
The increasing digitalisation of people’s finances is going to be pushed even further ahead should the European Central Bank’s plan for the digital euro come to fruition.
The plan for the digital euro is to be an electronic means of payment that is available free of charge to anyone to use. It will not be subject to interchange fees the likes of Mastercard and Visa charge on every transaction.
At the moment, the plan is to have the digital euro stored in an account set up in a bank. This can then be used to pay for items, either online or offline, with your phone or card. The idea is for the transaction to operate just like handing cash over without the need for intermediaries charging to facilitate the transaction.
The ECB is aiming to be ready for a potential first issuance of the digital euro in 2029, assuming all the legislation that underpins passing through the EU.
The increasing reliance on digital channels for payments should increase efficiency in the system as the handling of cash has its own negative effects.
However, as seen in the Revolut disruption, these systems are not foolproof and have the potential to cause widespread disruption to people.
CONNECT WITH US TODAY


Be the first to know the latest news and updates