Half of vulture fund borrowers can’t repay mortgages
Loan servicer borrowers paying just 58% of what they owe, Central Bank finds
Almost half of the homeowners whose mortgages are held by vulture funds cannot pay off any of their mortgage balance before they retire, according to new research by the Central Bank.
The analysis looked at more than 5,300 distressed mortgage cases from 2024 held by banks and loan servicing firms.
It found 45% of borrowers at loan servicing firms (LSFs) will be unable to clear any of their outstanding balance by retirement at their current rate of repayment. A further 22% will clear less than half.
LSFs are the non-bank firms which took on large books of distressed loans sold by Irish banks after the financial crash.
The figures contrast with the borrowers in difficulty with banks, where the equivalent figures were 18.5% and 16.3%.
The Central Bank analysis says borrowers at LSFs tend to be older, owe more, and are further behind on their repayments. The median age of LSF borrowers is 56, against 51 at banks. About a quarter of LSF borrowers are 65 or older, compared with one in 10 at banks.
The median LSF borrower pays €600 a month against a contractual payment of €1,029, or about 58% of what is due. Bank borrowers pay about 80%, or €936 of €1,162. The researchers found the median LSF borrower has built up arrears of €6,238, roughly double the €3,072 owed by bank borrowers. A quarter of LSF borrowers owe more than €33,611 in arrears.
Distressed borrowers at LSFs also pay a median interest rate of 5.65%, compared with 4.25% at banks. Most are on variable rates.
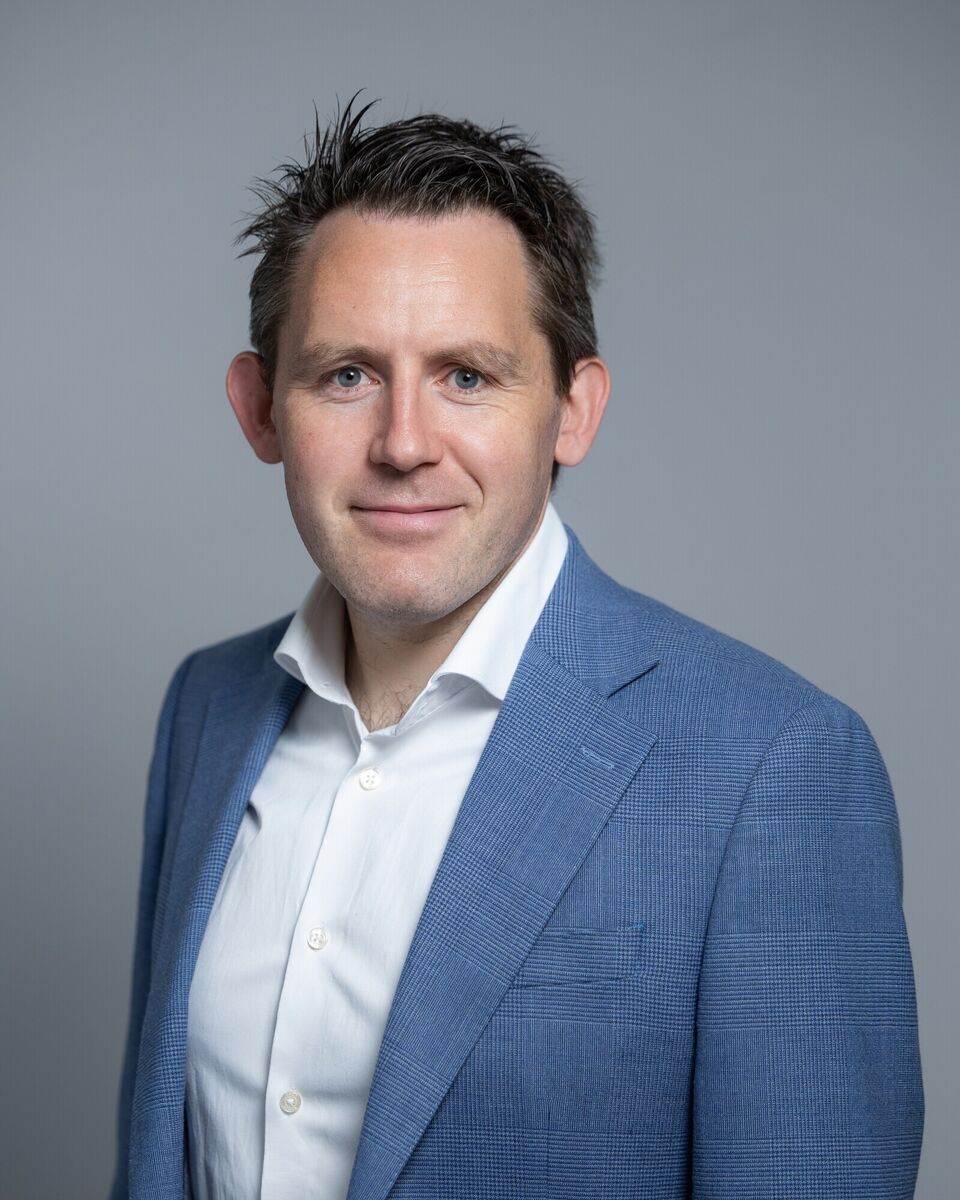
Stephen Curtis, chief executive of mortgage-to-rent provider Irish Homes, said a significant cohort of households had been “stuck” in arrears for more than 10 years, some for as long as 18 years.
He said marriage or relationship breakdown had often been a catalyst, particularly in the downturn after the Celtic Tiger.
“Marriage or relationship breakdown can transform a mortgage that was manageable on two incomes into a debt that one person has little realistic prospect of repaying,” he said.
“Many of those in long-term mortgage arrears today are now in their 50s or 60s, are mentally exhausted, and need a permanent viable solution.”
He said Central Bank figures showed an almost 7% annual increase in the number of arrears accounts being brought before the courts. This suggested the remaining long-term cases were increasingly ending in litigation.
He pointed to this year’s ECB rate rises, a slight uptick in unemployment, cost-of-living pressures and cooling house prices as factors that could push arrears up again.
Over the long term, mortgage arrears have fallen sharply. Home loans more than 90 days in arrears dropped from a peak of 12.9% of accounts in 2013 to 3.1% at the end of last year. But LSFs now hold three-quarters of those cases, up from a fifth a decade ago.
CONNECT WITH US TODAY


Be the first to know the latest news and updates