Retirement age mobility: Should I stay or should I go?
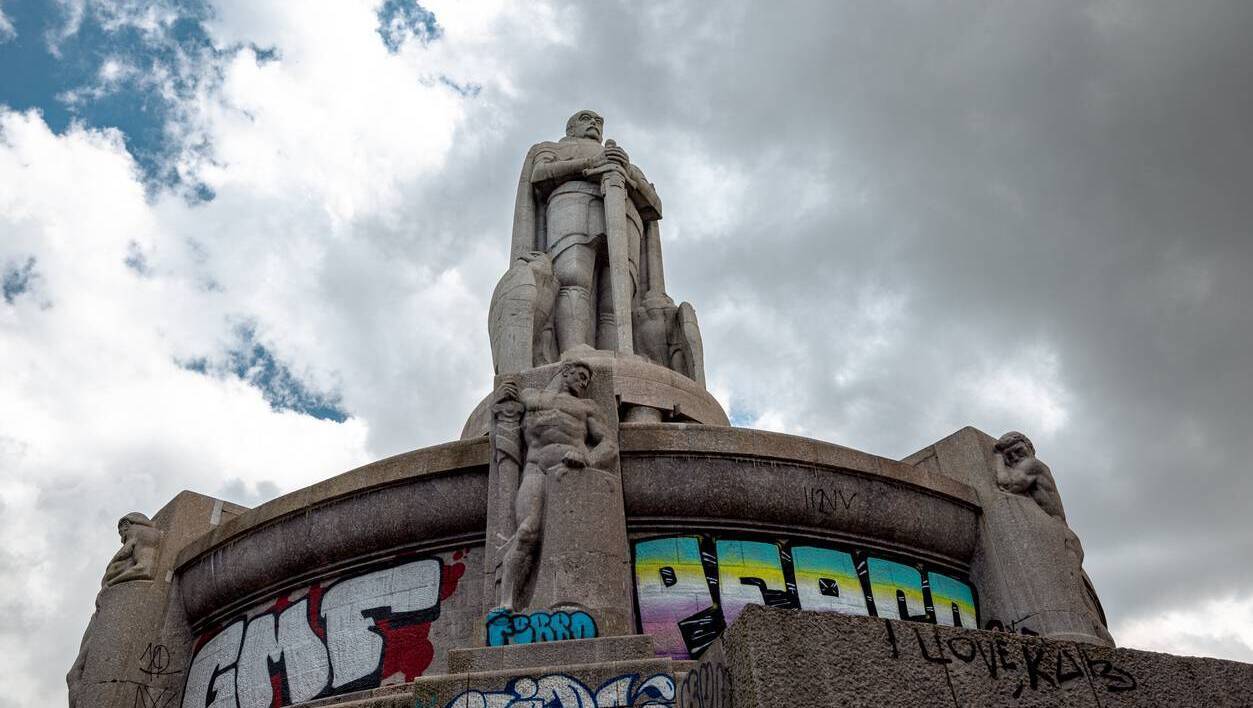
Otto von Bismarck, who introduced the modern concept of a statutory retirement age; the picture shows the Bismarck Monument, covered in graffiti, in Alter Elbpark, a monumental memorial overlooking the St Pauli district in Hamburg, Germany. Photo: iStock
, group managing director, Independent Trustee Company, analyses the implications should pension schemes move their retirement age to 66
Otto von Bismarck introduced the world’s first state-run old-age social insurance programme in 1889, creating the modern concept of a statutory retirement age.
The move was intended to appease disgruntled workers (although he set the retirement age at 70 when life expectancy was less than 60, so most would not benefit from it). Other countries ran with the concept until the notion of a retirement age has become engrained in the national psyche.
In its original form, retirement meant when you stopped getting paid by your employer and instead would receive some income from the State. The concept has expanded significantly since then with statutory retirement ages declining to 65 before increasing again to the current age of 66.
In the intervening years, private sector pensions have also flourished and have introduced an array of different retirement ages from age 60 onwards.
All that is now subject to change.
The Employment (Contractual Retirement Ages) Act 2025 gives eligible employees the possibility of continuing in service beyond their contractual retirement date until they reach State Retirement Age (currently age 66). This legislation came into force on 29th June 2026.
Note the legislation doesn’t compel the employer to grant the higher retirement age automatically. The employer is, however, obliged to objectively justify enforcing that retirement age. Equally an employee is not forced to work longer, they can still choose to cease working at an earlier retirement age provided in their employment if they wish to do so.
Interestingly, the legislation doesn’t apply to pension schemes, the majority of which tend to use a retirement age of 65. However, there are some with ages as low as 60.
The expectation is that many pension schemes will now move their retirement age to 66 to match this legislation. However, this may not be in the best interest of all members.
Consider a member of a pension scheme with an accumulated benefit of €150,000, a salary of €100k and 20 years’ service to age 60.
Under current Revenue Benefit rules that individual can access the full value of their pension fund €150,000 as tax free cash at age 60.
If, however, the normal retirement age of the scheme is moved to aged 66 and they still wish to leave at age 60, their retirement benefit will be subject to additional tax. Their maximum lump sum is now €150,000 x 20/26 = €115,385 which means the balance of €34,615 will be subject to tax at rates up to 50% – a total loss of more than €17,000.
Interestingly, if this employer retained the retirement age of 60 but permitted the individual to continue to work to age 66; the individual would be able to draw some or all of their retirement benefits at age 60. The receipt of pension benefit would no longer be dependent on ceasing to work.
This level of flexibility looks very attractive and no doubt many employers and pension schemes will give it serious consideration. However, one word of caution, the manner in which risk benefits work will need to be checked.
Typically, life cover and income protection cease at retirement age. So, leaving the retirement age at an earlier date may mean that some employees are working without cover.
This isn’t necessarily as serious as it sounds. If age 60 was your retirement age all along, then cover would in any case have ceased at that age.
If, however, the pension scheme is now moving back to this earlier age to achieve maximum flexibility for its members, then it will be vital that the position on risk benefits is checked. Ideally, they should be capable of continuing for those members who remain in service after age 60.
Another example of the flexibility that an earlier retirement age provides relates to the type of benefit received. If an employee continues in work beyond the normal retirement age specified in the scheme (say age 60) they can avail of one of three options:
- Take their lump sum and pension from age 60.
- Defer the lump sum and pension until the date they actually retire, or
- Take the lump sum and defer the pension.
Jo, aged 60, is working in employment where the pension scheme has a normal retirement age of 60. It suits Jo to continue working beyond age 60 and her employer readily agreed to this. However, Jo also has plans to go with her family on a cruise to Antarctica and the pension lump sum is crucial to funding this. Rather than needing to wait until she actual retires Jo can choose to access her pension lump sum now without affecting her right to work or her right to continue funding additional pension benefits.
Not only can Jo enjoy this once in a lifetime cruise. Her decision to continue to work means her pension benefits are not depleted by the withdrawal of the lump sum as:
- Continuing to work to age 66 means she will not need to start pension income until age 66, giving her pension fund another 6 years of growth. 6% growth per annum could add 40% to her fund.
- Retiring at a later date means annuity rates are likely to be better at that age.
- She can continue to fund additional contributions over the 6-year period to age 60 with a personal maximum funding of 40%.
The new legislation is intended to facilitate workers continuing in employment to age 66 when their State Pension benefit kicks in. The presumption from many is that pension schemes will adjust their retirement ages to 66 also. However, this won’t suit everybody and great care should be taken in developing an appropriate solution.
In the examples above some of the benefits of a retirement age of 60 were highlighted. Properly structured such schemes will provide people with a good Clash – “should I stay or should I go”. And if they do stay the pension scheme “it will be double”.