Pensions Council of Ireland: 'Optimists plan ahead and enjoy a long life'
Planning for positive outcomes: Retirement early isn’t about mentally hanging up your boots, it’s about considering and planning for the trajectory of a longer life. Photo: iStock
In springtime, winter is hard to contemplate. This might be the reason why, for young people, pension planning can seem low priority.
Asked why someone in their 20s or 30s should be thinking about retirement now, when it may be 30 or 40 years away, Retirement Planning Council of Ireland, CEO, Laura Farrell, says it’s because thinking about retirement early isn’t about mentally hanging up your boots, it’s about considering and planning for the trajectory of a longer life.
“It’s about generating options to meet the needs and wants of future you, who is probably going to live well beyond the current traditional retirement age,” she continues. “Retirement is less and less a fixed future point. Today’s 20 and 30 somethings will most likely have a much more multi-phased approach to how their work fits with their life as they age. A hard stop on work as a relatively young sixty-something is likely to feature less and less.”
Agreeing that much has changed about retirement planning that makes financial resilience particularly important for younger generations, she says: “The structural landscape has shifted completely. Previous generations benefited heavily from Defined Benefit (DB) pensions, relatively predictable housing costs, and to a greater degree, secure long-term employment. Today, the onus has largely flipped to the individual to navigate and plan.”
According to CSO figures, published in April this year, one in three workers aged 20 to 69 had no supplementary pension cover in 2025, rising to four in five among those aged 20 to 24.
Among those without any form of pension cover, affordability was the main reason given by 58 per cent of those aged 55 to 69. Among workers aged 20 to 24, 69 per cent said they’d no cover because they never got around to organising it, or they intended to do so at a future date.
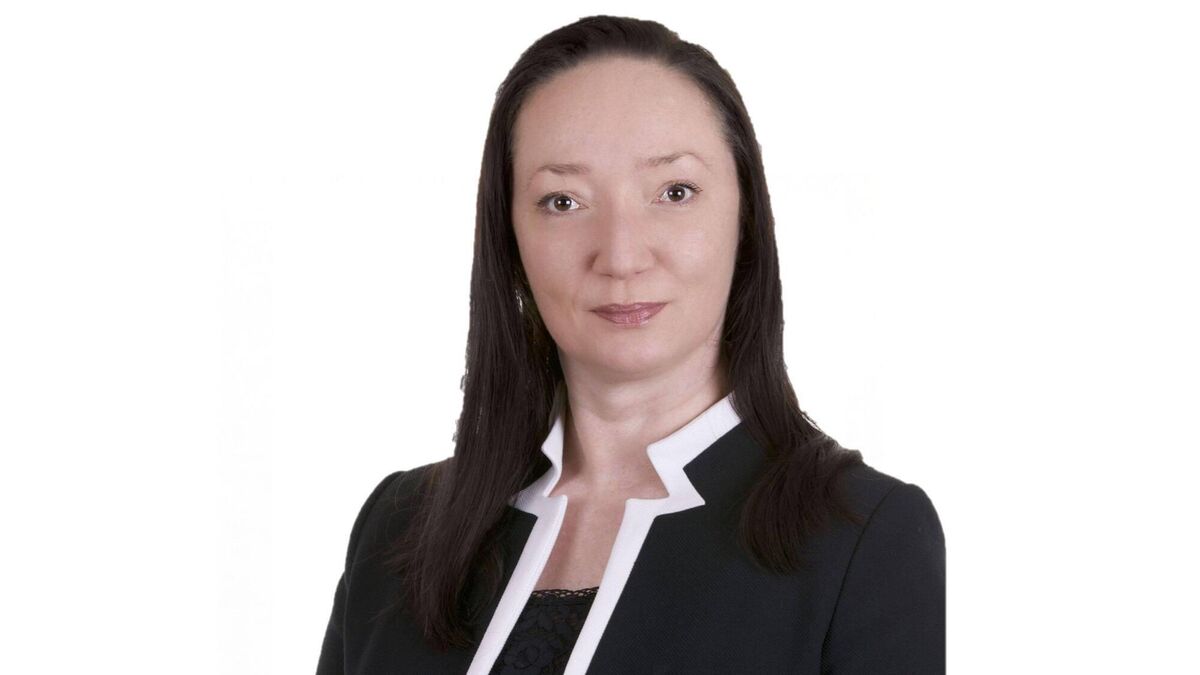
Asked whether younger people are likely to face a different retirement landscape from their parents’ generation, Farrell replies: “Fundamentally, yes. First, the demographic pyramid is inversing; dependency ratios mean state systems worldwide - ours included - are under greater pressure. Second, housing status is changing. Fewer retirees will enter later life as outright homeowners, meaning rent costs will persist post-retirement. Finally, the boundaries of retirement are blurring into more "phased retirement" transitions rather than an abrupt exit from work.”
Balancing saving for retirement with more immediate pressures, such as rent or mortgages, childcare, and other living costs, is no easy task. For younger people struggling with that, Farrell says: “It is not an all-or-nothing equation. We need to view retirement saving not as a competing expense, but as a non-negotiable fixed item - even if initially small – in our personal budget. If you wait for life to become less pressure-ridden in terms of immediate financial asks, before saving, you’ll most likely start too late, if at all.”
Deloitte’s 2026 Gen Z and Millennial Survey, revealed that this cohort are seeking stability before committing to major decisions. Financial strain has become a defining feature of how these generations work, live, and plan for the future, with 44 per cent of Irish Gen Z and 63 per cent of Irish millennials identifying cost of living as their top concern. Bearing this in mind, we have to wonder whether it’s realistic to expect younger workers to make significant pension contributions when many are struggling with the cost of living.
Farrell says it can feel as though we are asking younger generations to save for a retirement they may struggle to afford. “Rents, cost-of-living increases and childcare, place heavy strain on young adults. However, framed properly, saving early isn't a penalty, it's a protection mechanism against potentially even greater financial vulnerability in later life.
“So, while we shouldn't expect 20 to 25 year olds to be able to contribute a significant proportion of their salary while struggling with their rent, what is realistic and essential, is establishing the habit - even if small. With that, marginally escalating the contributions with every occasion of a salary raise, builds long-term wealth without overly impacting your current standard of living.”
For twenty-somethings wondering about the benefit of starting a pension now compared with when they’re in their 30s or 40s, Farrell says it’s the difference between working with the tide and swimming against it: “Starting in your 20s puts time on your side. Starting in your 40s means you have to contribute vastly higher percentages of your income just to catch up to where the 25-year-old landed with less effort.”
While pension is an important part of financing retirement, it’s not the only factor. Asked to briefly describe how retirement planning should ideally be about more than simply building a pension pot, Farrell replies: “A pension funds your life, but it doesn't give you a life. Research indicates that a successful retirement rests on many other pillars, including health, social connection, continuous learning, and a clear sense of identity once the workplace title is gone. Money provides security. Purpose provides fulfilment.”
According to CSO figures published in September, the estimated inflation for households comprised of under 35s, was 3.9 per cent in the year from June 2025 to June 2026, compared with 3.4 per cent for all households. Among those renting, estimated inflation was 25.9 per cent, over the five years from June 2021 to June 2026, compared with a figure of 22.2 per cent for homeowners who owned their home outright, over the same five-year period.
Given the financial pressure being experienced by young people from all sides, it’s common to hear them opine that they’re too young to worry about retirement. Farrell frames it this way: "Don't think of it as retirement; think of it as investing in your future independence. You aren't planning for old age, you are giving yourself options to pivot, reduce stress, change careers, or step back on your own terms.”
While struggling with rent, debt and saving to buy a home, young people are also told to ‘start saving early’ for their pension. For those pondering why failing to do so could be one of the biggest financial mistakes they can make. Farrell has this to say: “Because you cannot buy back time. Catching up in middle age requires sacrificing a larger percentage of your mid-career earnings at a time when costs - such as mortgages and teenage children - are often at their absolute peak.”
CONNECT WITH US TODAY


Be the first to know the latest news and updates