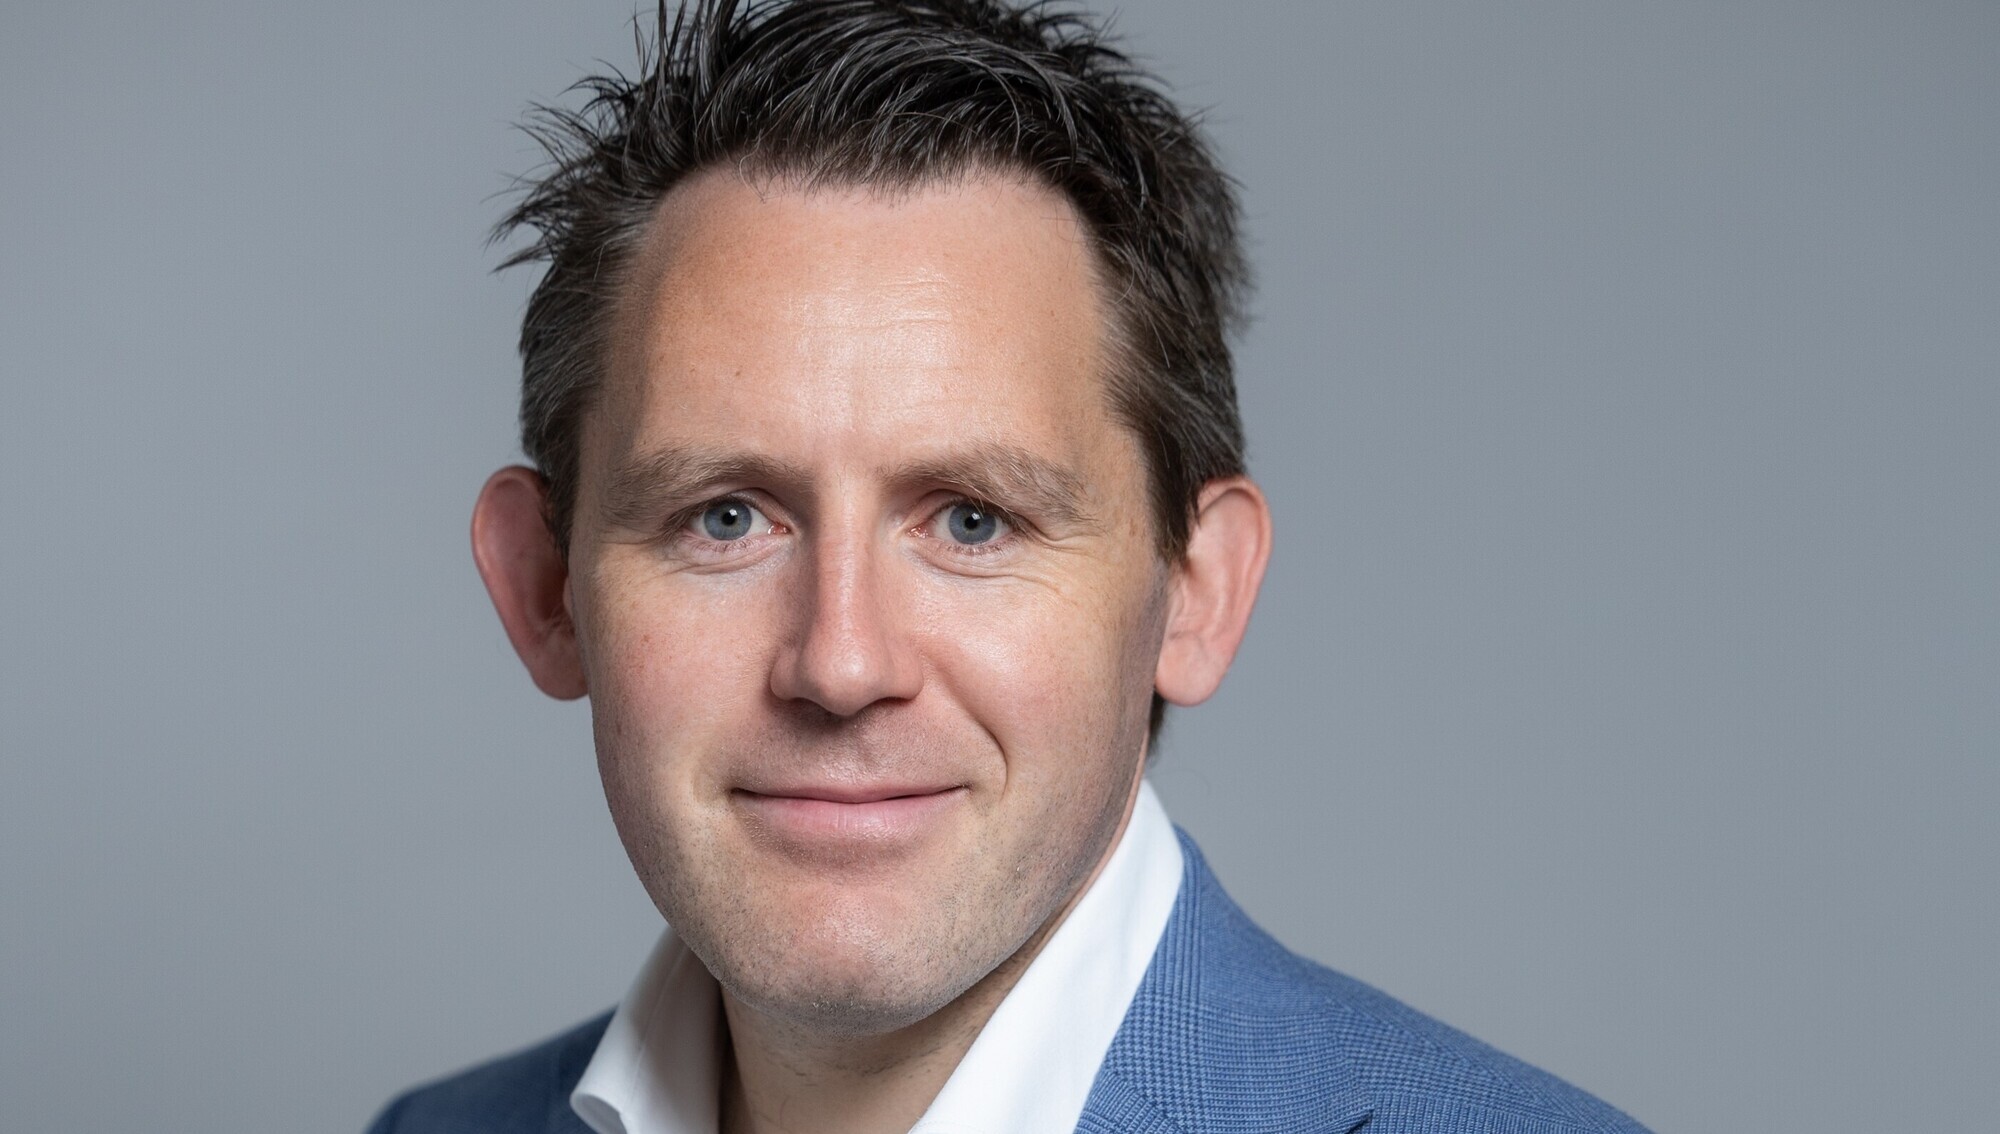
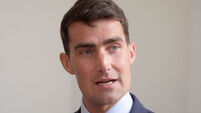
Name: Stephen Curtis
Occupation: CEO, Irish Homes
Background: Ireland’s largest provider of the Mortgage to Rent scheme - a State-backed initiative allowing homeowners facing long-term mortgage arrears switch to renting as a social housing tenant.
Irish Homes operates across all 31 local authority areas in Ireland, with the Mortgage to Rent scheme having recently passed 3,000 completed cases nationally.
Aimed at people whose mortgages are no longer sustainable, it allows them to give up ownership of the property but stay in their home as social-housing tenants.
Recent analysis of more than 600 cases by Irish Homes, the country’s most active provider of Mortgage to Rent (MTR) solutions, found that on average mortgage holders who availed of the scheme were in 27% negative equity on their properties.
Irish Homes says this is evidence that negative equity remains a significant driver of mortgage arrears and that despite rising property prices nationally, many households remain trapped by mortgage debt that exceeds the value of their homes.
However, the counterpoint is that continued house-price growth could narrow the window of eligibility for some distressed homeowners, since the Mortgage to Rent scheme caps both property values and the amount of positive equity permitted.
The maximum permitted value ranges from €265,000 to €515,000, depending on the county. Similarly, permitted positive equity can be no greater than €40,000 or €50,000, also depending on the county. In effect, a homeowner who qualifies today could become ineligible if their property’s value rises above the applicable limit.
“Many of the people reaching us are still in negative equity, with mortgage debt that their property cannot fully cover,” explained Irish Homes chief executive Stephen Curtis.
“They may have lived with that burden for years and believe there is no sustainable way forward. Property values are increasing in many parts of the country. And while that may sound like positive news, for somebody considering Mortgage to Rent, if their home becomes too valuable or builds up equity beyond the scheme’s limits, an option available today may no longer be available later. So, waiting to avail of an MTR solution can carry a real risk.”
He underlines the essential Irish Homes message: “Do not wait until your circumstances reach a crisis point. If your mortgage is unsustainable, seek an assessment now and establish whether you qualify.”
Rising prices are not, in themselves, a solution for households in this position, he says. With average negative equity of 27% on outstanding mortgage debt of over €325,000, a recovery in property values would need to be substantial and sustained before a sale could realistically clear the debt owed.
“Even where a sale is possible, it would not solve the underlying housing need — because many of these homeowners don’t want to move away from everything they know — schools, family supports, communities. This is particularly pertinent for older homeowners who have lived for many years in a certain area. While it is never a first port of call, for the reason outlined, MTR is can be a very workable solution because it allows people to remain in their home and community.”
Mortgage to Rent enables eligible homeowners in serious mortgage arrears to surrender ownership of their property while continuing to live in it as social housing tenants. Eligibility depends on several factors, including mortgage circumstances, social-housing eligibility, income, household needs, property value, and the level of equity in the home.
Analysis conducted by Irish Homes revealed a number of common characteristics of mortgage holders who avail of this solution, including the average outstanding mortgage debt was €325,968, while the average level of negative equity was 27%.
The average open-market value of the properties analysed was €256,299, with values ranging from €100,000 to €465,000. Single-parent families accounted for approximately 41% of the cases analysed, making them the largest household group represented. A further 31% were single adults living alone, while approximately 28% were couples or multi-adult households.
More than half of the households examined had no dependants. A further 20% had one dependant, approximately 12% had two, and almost 15% had three or more. The homes are located across the country and in different types of communities — 49% were suburban, 29% rural, and 22% urban. More than seven in 10 participants were in their 50s or 60s, with those in their 50s the largest single group, closely followed by those in their 60s. The oldest participant was 81.
“Marriage and relationship breakdown has often been one of the catalysts for arrears, particularly when coupled with the deteriorating economy following the Celtic Tiger era, which is when most of these arrears cases originally began. Separation can leave a household attempting to meet mortgage repayments and other living costs from one income, sometimes while also supporting children,” he added.
“Marriage or relationship breakdown can transform a mortgage that was manageable on two incomes into a debt that one person has little realistic prospect of repaying.”
The analysis of the data shows that mortgage arrears are not short-term financial difficulties affecting one narrow section of society — with single parents, people living alone and older homeowners having carried unsustainable mortgage debt for a prolonged period. Irish Homes says homeowners who have exhausted other avenues and who believe their mortgage is no longer sustainable should contact their lender or an appropriate mortgage arrears adviser promptly to determine whether Mortgage to Rent may be available to them.
Irish Homes spends an average of €56,432 refurbishing and improving each acquired property. “People should not assume that they earn too much, are too old, or have struggled for too long to explore their options,” said Mr Curtis. “They should obtain advice and have their circumstances assessed against the current criteria. But doing nothing while arrears continue and the value of the home moves closer to, or beyond, the scheme’s limit is not something that’s going to benefit anyone.”

Cancel anytime
CONNECT WITH US TODAY
Be the first to know the latest news and updates