Let the buyer beware tech stocks
Is that the sound of a bubble popping, or is it just a little bit of steam being let off?
Some $275bn was wiped off the value of internet companies in just seven days — something more than a mere blip.
A lot of people in the markets are scratching their heads and wondering whether the sharp setbacks, coming on top of a prolonged period of weakness in social media and biotech stocks is a sign of real trouble ahead.
The Financial Times reported that investors had cooled on the latest listings, with shares in recently floated internet companies such as JustEat and Boohoo.com falling below their offer prices. The Israeli digital ad firm Matomy announced that it was pulling its £300m London IPO.
Nerves appear frayed. We have been here before, of course. Reams of valuable paper have been used up in lengthy dissertations about the disastrous slump in the share price of Facebook following its stock market launch in 2012. Last year, its price rebounded with a vengeance, gains which were consolidated until recently. Of course, financial markets move all over the place, being manic depressive by nature.
The Nasdaq, the US tech stock index, tumbled by over 3% on Thursday, its worst daily decline since 2011. Yet over in the sovereign bond arena, Greece — the mad old indigent relative in the attic of the eurozone — was suddenly the belle of the ball again, having successfully raised five-year money in the markets with investors actually queuing around the corner to take up the stock.
It is hard to tell at this stage which of these stories, tech slump or the Greek issue, is likely to be the one most lasting in impact. Certainly, in equity markets, the bears are back roaming among the bins. All the talk is of ridiculously stretched valuations.
Investors are back in search of dividends, shifting towards safe, dull stocks. The spectre of the dotcom bust of 2000-1 is looming, though calmer souls insist that valuations are nothing like as stretched as they were then.
Nevertheless, after the recent deluge of IPOs involving stocks with a strong social media slant, investors may again be starting to wonder whether they might not have been sold a few pups again. Last week, Katherine Rushton of the Daily Telegraph reminded readers of the glory days of the dotcom boom when the internet company, Lastminute.com was valued at £571m on its initial flotation.
This was also the time when Fran Rooney’s Baltimore Technologies entered the FTSE 100 and had a higher market value than Bank of Ireland (at a time when the bank was a stock market giant and not a North American bottom fisher’s paradise). Lastminute.com jumped from 380p to almost 500p before crashing down to earth within weeks. Co-founder Martha Lane Fox was later badly injured in a crash before re-emerging as a promoter of social media activities in Britain.
Rushton, writing last Monday, warned with some prescience that there were “worrying signs that a bubble was forming”, pointing to the glut of tech companies that have gone public at valuations that seem to be totally out of kilter with their financial track records. Others insist that valuations are nothing like as frothy as around the millennium.
They point to a price earnings ratio among US Standard & Poor’s stocks of 19 compared with almost 30 in late 1999. What is clear is that pricing developments do not occur in a vacuum. Enthusiasm about social media has spread rapidly from its base in the youth culture across a population seduced by the expanding smorgasbord of information and communication devices, leaving certain old codgers gasping and trampled in the dust.
Some clever investors have themselves caught this rollercoaster wave and are promoting stocks among the public with a view to monetising this investment.
But markets always tend to overreach themselves.
Over the years, the hype surrounding certain bio-tech stocks has been particularly egregious, with false hopes of cures being circulated with a view to quick profit — all in the best tradition of the wily 19th century American ‘medicine man’ peddling his dodgy potions.
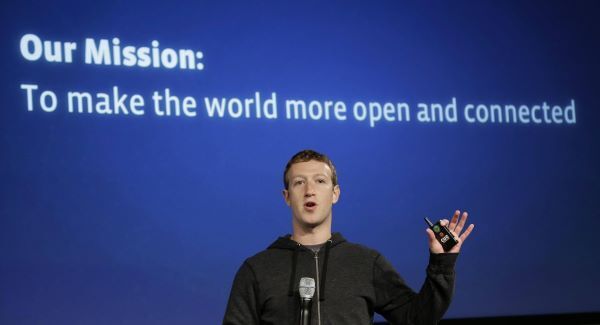
The Facebook IPO of May 2012, among the most hyped in history, certainly turned out to be a rollercoaster affair. The stock fell by over 4% in its first 90 minutes of trading. Having floated at $45, it hit a low of $17.55 the following September before staging a dramatic recovery in 2013. Despite a decline of around 10%, it is still well ahead of its flotation price.
For a while, Mark Zuckerberg’s entity appeared to symbolise all that was wrong about early-21st century capitalism. As Guardian journalist Dean Baker put it: “In this case, there will have been an enormous transfer of wealth from the purchasers of Facebook stock to those able to cash out following the IPO. This will make many of those on the inside of the company fantastically wealthy.”
He added: “In the last two decades, the economy seems to have created many openings for people whose primary skill is lifting money out of other people’s pockets, not in doing anything productive. Wall Street is the centre of such practices.”
But then Facebook rebounded, appearing to rout its critics. Paul La Monica of CNN Money made a dramatic confession that he had been wrong all along to condemn Facebook and its IPO.
Last September, La Monica wrote: “I’m not looking forward to dining on a small black bird. But here goes. It is time to eat some crow.” The writer had been tripped up by a doubling in the Facebook share price since he had published a derisive piece on the company. The Facebook turnaround was achieved, in large part, as a result of the release of data showing its mobile ad revenues were soaring.
This gave investors something to cling to and draw inspiration from, serving as a reminder that amid all the financial market waves, some real tangible changes are occurring in a key wealth-generating sector.
La Monica was reluctant to bet against Facebook again while acknowledging that with challenges posed by rivals such as Google and Twitter, the Facebook turnaround is by no means guaranteed.
Yet real doubts persist when it comes to IPOs and the interests of small shareholders located outside the golden circle at the heart of the flotation.
The temptation for shareholders, whether they be founder entrepreneur or provider of outside venture capital, to milk it to the maximum can be overwhelming, particularly in an environment of investor exuberance.
Famously, promoters have come badly unstuck as a result of mispricing, the pulled Guinness Peat Aviation flotation of 1992 being perhaps the most famous example.
Some attempts have been made to crunch some long-term data on the performance of newly floated companies.
Late last year, the Daily Telegraph’s ‘New Money’ section commissioned some research from Interactive Investor and Dealogic into the share price performance of 287 companies floated over the preceding five years. And the conclusion? Investors lost on average 8%, overall. Ordinary investors fared worst as they missed out on immediate surges in share value on the flotation day while the performance of the IPO stocks varied wildly depending on when the launch took place.
Listings in 2008 and 2011 had produced negative returns for investors up to November 2013 of 26.4% and 27.85, respectively. However, people investing in 2009, 2012, and 2013 were ahead to the tune of 15.7%, 20.1%, and 19.7%. Timing remains crucial.
The message to investors is clear: Ignore the hype. Study the prospectus document which often contains plenty in the way of warnings and wait to see whether the founders or cashing out before plunging in.
As the old Roman would say: Caveat emptor.
CONNECT WITH US TODAY



Be the first to know the latest news and updates