When it comes to your pension, advice shouldn't be optional
Tailored pensions advice: A Qualified Financial Advisor (QFA) will give you answers that depends on your own circumstances, not a generic reply.
, head of marketing and communications, Ask Acorn, offers advice on the importance of understanding your pension
Pensions are already one of the top two topics people most want financial guidance on, behind only saving and budgeting.
Yet only 23% of Irish adults actually use a financial adviser, according to Ask Acorn's own research into financial advice preferences, published this September. For a decision as personal as how to save for retirement, that gap matters.
Nowhere is that clearer than with Ireland's new workplace pension scheme, My Future Fund. It launched on 1 January 2026, automatically enrolling employees aged between 23 and 60 who earn more than €20,000 a year and aren't already in a workplace pension — putting more than 835,000 people into a pension decision almost overnight, many for the first time.
Nine months in, it's a genuine success story on its own terms: fewer than 4% have opted out, well below the roughly 10% seen in the UK and 12% in New Zealand's equivalent schemes. But very few of those 835,000 will have sat down with an adviser first.
That's not a criticism of the scheme — My Future Fund was never designed to come with advice attached, and it's done exactly what it set out to do: get people saving, many for the first time, who had no pension at all before it. Roughly one in three private-sector workers fell into that category before the scheme began. That part of the story is straightforward and worth recognising.
What a default scheme can't do is make the decision that's specific to you. Pensions are one of the few financial products where the right answer depends heavily on your own income, tax position and goals — which is exactly why they're also one of the areas where advice adds the most value.
Contribution rates for the scheme's first three years are set at 1.5% of pay from the employee, 1.5% from the employer, and a State top-up worth €1 for every €3 the employee puts in, up to a salary cap of €80,000. The table below shows how a €700 total contribution compares with putting the same amount into a private pension, where tax relief — unchanged in Budget 2026 — still applies at 20% or 40% depending on income.
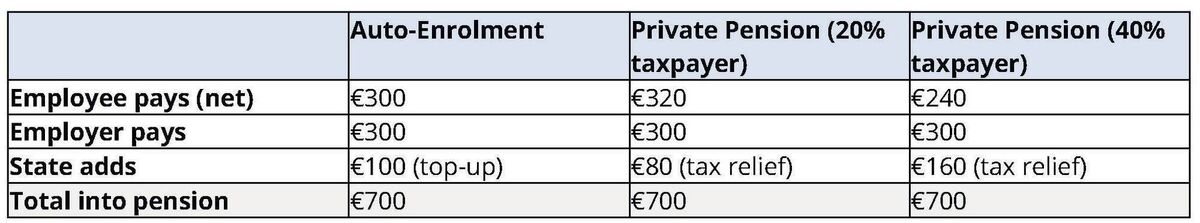
Look closely at that table and you can see what's at stake. A 20% taxpayer and a 40% taxpayer get a different outcome from an identical €700 contribution — and for a higher-rate taxpayer, picking the wrong option could mean paying more for the same result, simply because nobody worked out which route suited their own tax position. That's not a flaw in My Future Fund. It's one of the clearest illustrations going of why pension decisions specifically benefit from individual advice, rather than a generic default or a quick search online.
This is the kind of ground a Qualified Financial Advisor (QFA) would cover with you in a single conversation — each with an answer that depends on your own circumstances, not a generic one:
- Is a fixed 1.5% / 1.5% / 0.5% contribution enough for the retirement you have in mind — or would Additional Voluntary Contributions, only available outside My Future Fund, get you there faster?
- Would you get more from tax relief than from a State top-up? My Future Fund contributions come with a State top-up rather than income tax relief; for a higher-rate taxpayer, a PRSA or private pension can work out cheaper for the same net benefit.
- How much control do you want over how it's invested? My Future Fund uses a single default fund; private pensions and PRSAs typically offer a wider range of options.
- Who's going to keep this under review as your circumstances change? My Future Fund doesn't come with ongoing advice; a private pension or company scheme usually does.
If you're already enrolled and considering your options, there's a two-month opt-out window that opens six months after enrolment (the first one ran from July to the end of August 2026), reopening every two years if you're automatically re-enrolled. Outside that window, you can suspend contributions instead, for up to 24 months. Before deciding either way, it's worth knowing: NAERSA's own figures show the average refund to someone who opted out was €331 — while, on average, €440 in employer and State contributions stayed behind in the fund.
Tús maith leath na hoibre — A good start is half the work My Future Fund has done exactly what it was designed to do, and done it well: get hundreds of thousands of people saving who weren't before, with far less resistance than anyone predicted. That's worth recognising.
But it hasn't closed the advice gap this piece opened with — and it was never going to. Only 23% of Irish adults use a financial adviser, and nothing about being auto-enrolled changes that. Getting everyone saving and getting each person the right outcome are two different jobs. For most workers, the sensible next step isn't to question whether My Future Fund is working. It's to close that gap yourself, by asking a Qualified Financial Advisor whether it's working for you specifically.