Financial planning board launches new tool to help consumers assess retirement savings
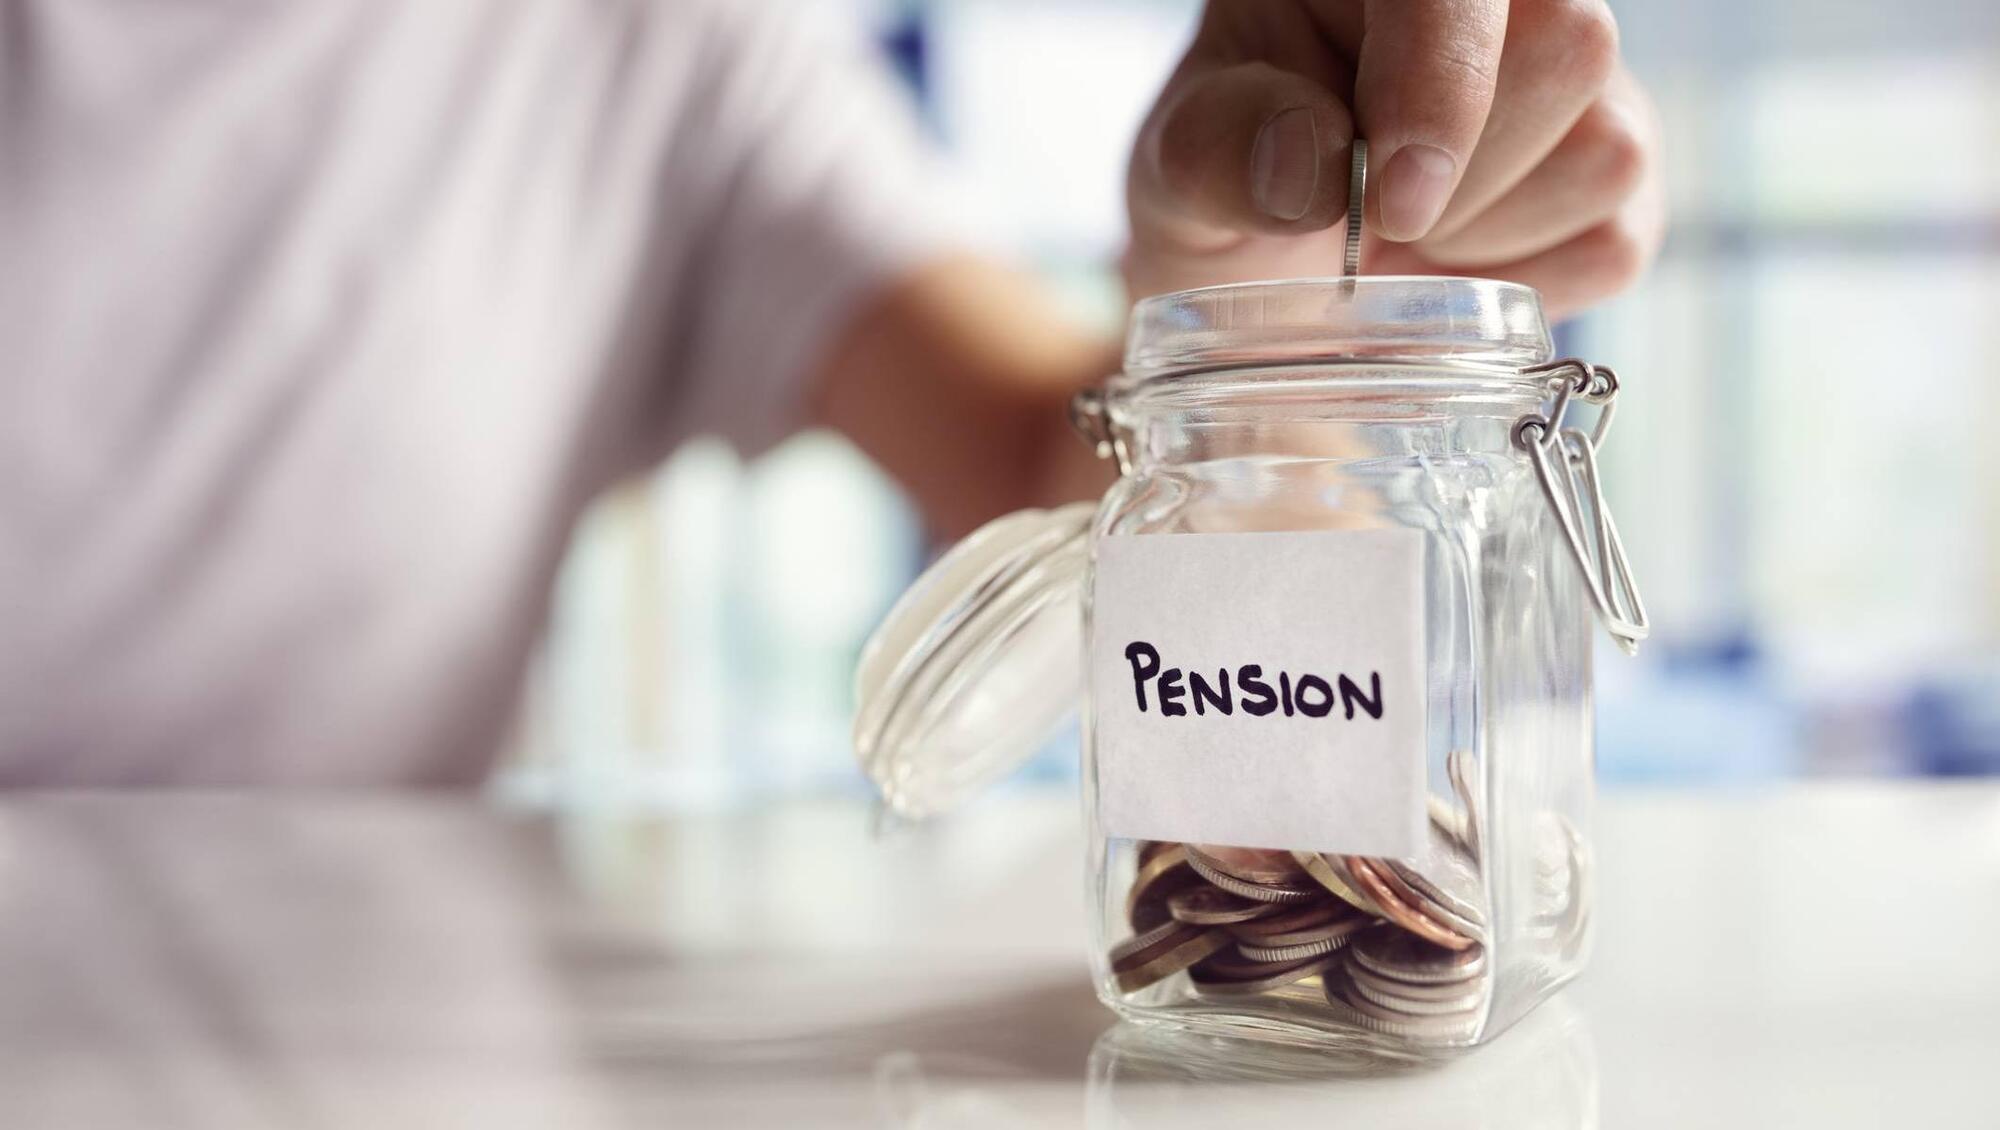
Financial Planning Standards Board has launched the Prime Retirement Index (PRI), a benchmark designed to help savers assess retirement readiness now and identify potential shortfalls earlier.
The organisation that oversees financial planners in Ireland has launched a new benchmark to help consumers assess their retirement savings needs, as nearly 80% of people say they are unprepared for retirement,
The Financial Planning Standards Board (FPSB) Ireland, the body that sets the professional standards for financial planners in Ireland and represents the country’s 1,100 certified financial planners, on Tuesday launched the Prime Retirement Index (PRI), a benchmark designed to help savers assess retirement readiness now and identify potential shortfalls earlier.
FPSB Ireland said its research found while 74% of respondents said they managed their day-to-day money well, 79% felt financially unprepared for retirement and 52% worried their savings would not last.
The PRI provides an age-related reference point against which accumulated retirement assets can be assessed. According to the index, someone aged 35 should have at least one year’s salary already set aside for retirement.
Someone aged 45 should have three times their annual salary set aside, by age 55 seven times a person’s annual salary should be set aside, and by age 65 it should be 11 times their annual salary.
As an example, FPSB Ireland said a saver aged 41, earning about €65,000 a year and with €70,000 in retirement savings would have 1.1x their annual salary when it should be 2.2x, which means they are at 50% of their target.
“At 11x salary the target retirement pot is €715,000. At a 4% drawdown, that is €28,600 in income. Add the State pension of €15,500, [which] brings the retirement income to approximately €44,100,” FPSB Ireland said.
“However, if the saver stays at 50%, they reach 5.5x — generating total income of €29,800 including the State Pension, a shortfall of €14,300 per annum.”
Read More
FPSB Ireland said identifying these shortfalls early means a saver can add more to their pension pots early to reach targets in time for retirement.
“A saver starting at age 35 with 50% of the PRI target and increasing total contributions to 14% reached the target in 99% of tested scenarios by age 65, without an additional lump sum. This fell to 52% when starting at 45 and 22.5% when starting at 55,” the board said.
Chief executive of FPSB Ireland Emer Kirk said “nobody should get to their 50s and discover for the first time that the pension they have spent years building may not provide the retirement income they expected”.
“The central message from this analysis is that timing matters. A gap that may be manageable earlier in your career can become significantly more difficult to address as retirement gets closer.
“The earlier a potential shortfall is identified, the more time there may be to understand the options available, make informed decisions and, where appropriate, seek professional financial advice.”
FPSB Ireland said for those who find themselves behind in their savings targets, there are options such as increasing contributions, adding a lump sum, reviewing investment strategy, drawing on other assets, or changing retirement timing.

CONNECT WITH US TODAY


Be the first to know the latest news and updates