Are you financially literate? Nine money questions everyone should be able to answer
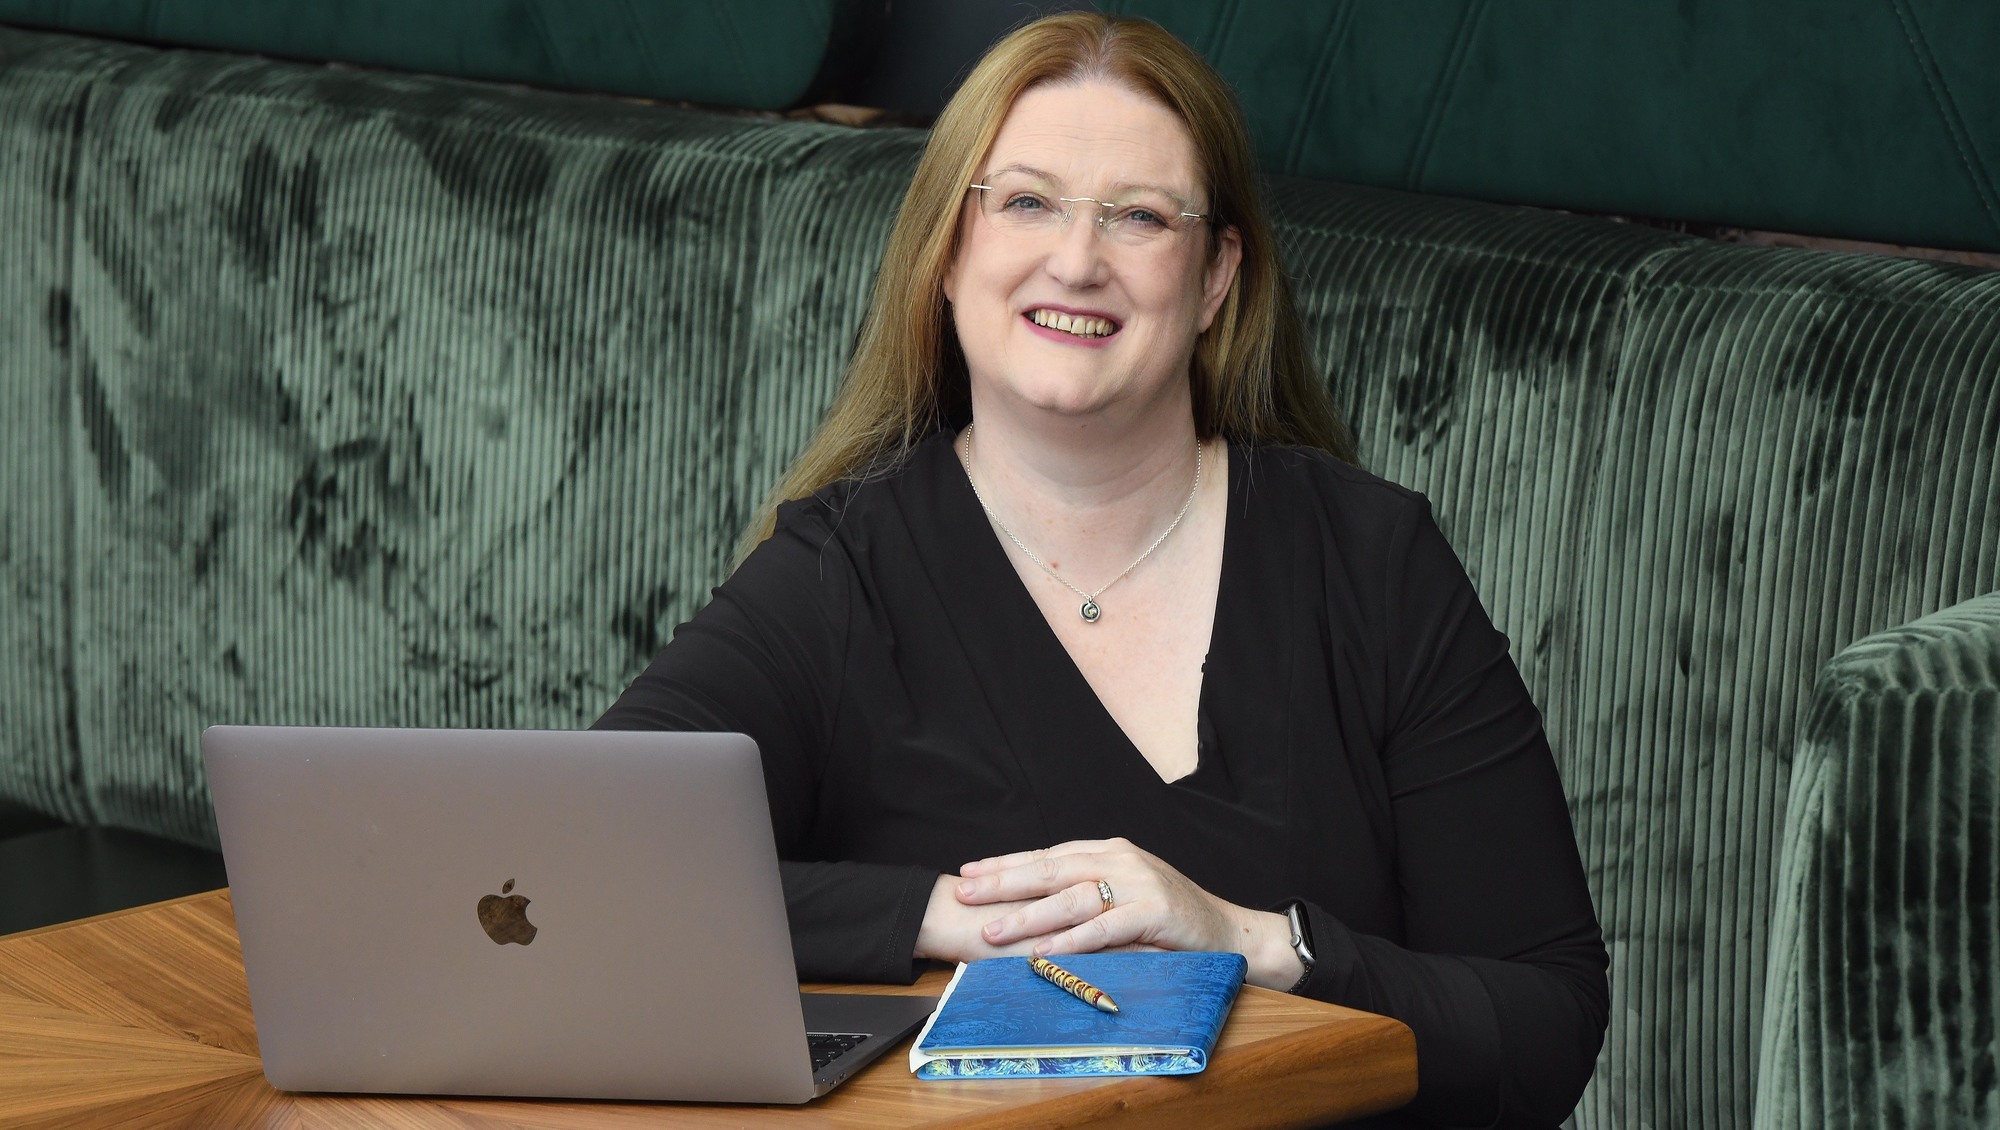
Savvy spender Caitriona Redmond shares her must-ask money questions. Picture: Moya Nolan
For a nation obsessed with money, we don’t like talking about our personal finances.
This sits in a strange contrast to the sayings that do include references to money: ‘He’s the reason the fifty pence piece had sides on it,’ or ‘They’re so mean, they could peel an orange in their pocket,’ or ‘He married her for road frontage.’
‘Thanks Penneys’ is a joyous refrain that reveals a bargain when somebody likes an outfit — but chat skims the surface when it comes to talking about money.
Safe to say, we are interested in all things financial but not willing to discuss what we are personally up to. Instead, we are happy to discuss the vagaries of other people’s finances.
This leaves many without someone to turn to for advice or to know what to do when they are in financial difficulty, let alone plan for the future.
The first step to becoming more financially literate is answering these simple questions.
1. What are you worth?
Of course, every individual is priceless but this is a financial calculation. Take what you own, subtract what you owe, and this is your worth.
For example, if Mary owns a house worth €275,000 but owes €150,000 on her mortgage, her net worth is €125,000.
If Joe owns a mobile phone that would sell second-hand for €500 but he is paying €50 a month on his contract, with six months left, then the phone is worth €200 today. But it may be worth more than that today and less than €500 when the contract ends.
When calculating home insurance, many people neglect the value of contents, jewellery, and technology. How much are these worth to an insurer and to you?
Don’t forget any pension contributions accumulating in the background. While they may not be worth much to most people today, they have value at retirement or death.
2. Where is all your money going?
Unless you’re incredibly organised with a handwritten budget book and logging every single one of your purchases, then the chances are you are not confident of where your money is going. Sure, you may have a vague idea of what your weekly grocery shop costs and how much your accommodation is costing you but do you know where you’re spending your hard-earned cash?
To get a handle on this will take about a month. It involves keeping a copy of every receipt, noting what you spend your money on, and then categorising your spending. Are those mid-morning coffees essential? If so, put them under regular day-to-day expenses. If not, allocate the coffees under a recreational item.
This may be easier to manage with a spreadsheet, and there is a wealth of free templates online, including within Microsoft Excel and Google Sheets. You may be surprised at what is rapidly draining your finances.
3. Would you manage if your income stopped?
Do you have a contingency or buffer fallback account? Most Irish people will be entitled to some form of social protection, so there’s no need to hold as much as a full year’s income in a contingency fund. At a very minimum, you should have three months’ expenses on hand in case the worst happened and you lost your job.
Basic expenses should include accommodation, utility bills, insurance, transport, and food. These may not be as much as you realise and are easier to manage if you hit a brick wall.
How much of your day-to-day living expenses can you afford to drop in the event of a radical change in income? Could you do without hair appointments and your car, and could you reduce your discretionary spending?
4. How much do you (really) owe?
Returning to the earlier example of a phone contract. That’s where what you owe gets rolled into a monthly service cost. It’s still a debt owed, and most service providers charge an exit fee.
All service contracts are financial commitments, and these may be easy to exit or more complicated. Utility bills cost at least €50 per service (electricity or gas) to leave an existing provider.
Other annual commitments are property tax, TV licence, health insurance, car insurance, and home insurance. Each of these is due annually, and some are optional (such as health insurance or vehicle-related insurance) but you can expect these charges every year, so they should fall under the regular debts category.
Mortgage, rent, and loans are obviously on this list and should be included; self-employed people who don’t have tax deducted at source should also include income tax.
5. Are you paying yourself first?
Classic budgeting says to pay your debts first when you get paid. This concept tips that on its head.
By ‘paying yourself’, you are prioritising your future plans and then budgeting to pay the rest of your commitments. Say you earn €2,000; instead of spending first and saving what is left,
you should immediately move €200 (10%) into savings for the future. This could go toward your emergency fund or paying off certain debts (if that’s your priority). Then take care of the day-to-day bills.
As you’ve paid yourself as soon as your bank account receives the money, you get used to having less to work with, and it’s easier to adapt.
6. What will your pension give you and what will your life cost on retirement?
For most people in Ireland, retirement income will ideally come from a combination of sources. On a lower income with no private pension plans, it may simply be the State Pension, which is currently €299.30 per week at the maximum rate if you draw down at 66 and €328.90 per week if you draw down at age 68. While this rate will change in the future, it’s a decent benchmark to calculate your pension needs.
The newly established MyFutureFund will also affect the income people have in retirement but it’s difficult to calculate what that may be.
This is a very personal calculation; pensioners who own their homes may have fewer housing costs to worry about but more maintenance. Those who rent will have to factor this cost into the future.
Retirement can be expensive in ways we don’t appreciate when we’re working, though. With extra time on your hands, you may like to travel, spend time with family, take up new hobbies, or simply enjoy the things you couldn’t when working full-time. There are other, less fun costs to factor in, such as health insurance and unexpected bills.
What will your household spend be in a typical month and what will disappear when you stop working, and what will stay? What would you like to afford that you can’t justify today? And, finally, how much would you want left over for holidays, a meal out, or helping your family?
The best starting point for retirement planning isn’t: ‘How much is in my pension?’ It should be: ‘What do I want my retirement to look like and will the income I have coming in pay for it?’ This is an important insight to have, preferably well before retirement is on the horizon.
7. Are you making the most of your tax credits?
Irish residents are all entitled to the basic personal tax credit. The exact amount depends on your relationship status, and the Revenue Commissioners rely on taxpayers to inform them of any changes.
Tax credits reduce the income tax due to the Revenue Commissioners, and more credits are available depending on personal circumstances. An individual caring full-time can claim a home carer tax credit; parents of a child with a disability may be entitled to the Incapacitated Child Tax Credit. Each of these credits reduces taxable income and can increase take-home pay.
Even better news: You can now claim tax relief monthly for health expenses. This means taxpayers no longer have to wait until year-end to claim back on health-related costs. This can be especially helpful when a large expense comes up as it boosts disposable income.
The Revenue Commissioners are extremely helpful in this regard, and you can check your credits, along with raising any queries, by using the MyAccount service on revenue.ie.
8. Would you manage if life changed?
It’s difficult to envisage life even 10 years from now and, when looking ahead, people naturally mirror their existing lifestyle into the future. What would happen if you needed to take time off work to care for a family member?
How would your lifestyle change and could you afford it? In an ageing population, this is the reality that many households face.
If a long-term relationship broke up or your partner died, how would you manage your finances?
Making a will is vital. While challenging and terrifying in equal measure, it’s important to consider the future from these aspects. The Law Society of Ireland has excellent advice on their website, and making a will needn’t be an expensive outlay either. Organisations such as FreeWill.ie can help those over 53 who want to make a charity bequest in their will.
9. What does your financial freedom look like?
For some, financial freedom may mean not having to check the bank account before grocery shopping or being free from paying rent or a mortgage. For others, the goal is knowing the bills are comfortably paid from regular income and having the freedom to choose what to do with the money they have without worrying about the future.
Would your financial freedom involve not having a nine-to-five job or being able to escape from the shackles of your current career?
American writer and civil rights activist Maya Angelou once said: “You can only become truly accomplished at something you love. Don’t make money your goal. Instead, pursue the things you love doing and then do them so well that people can’t take their eyes off you.”
Is work, family, or travel high on your list of priorities for the future? Make a list of your lifelong goals; then follow it with the number of (realistic) steps that you have to take to achieve them.
Planning for financial freedom will take work and time.
CONNECT WITH US TODAY



Be the first to know the latest news and updates